
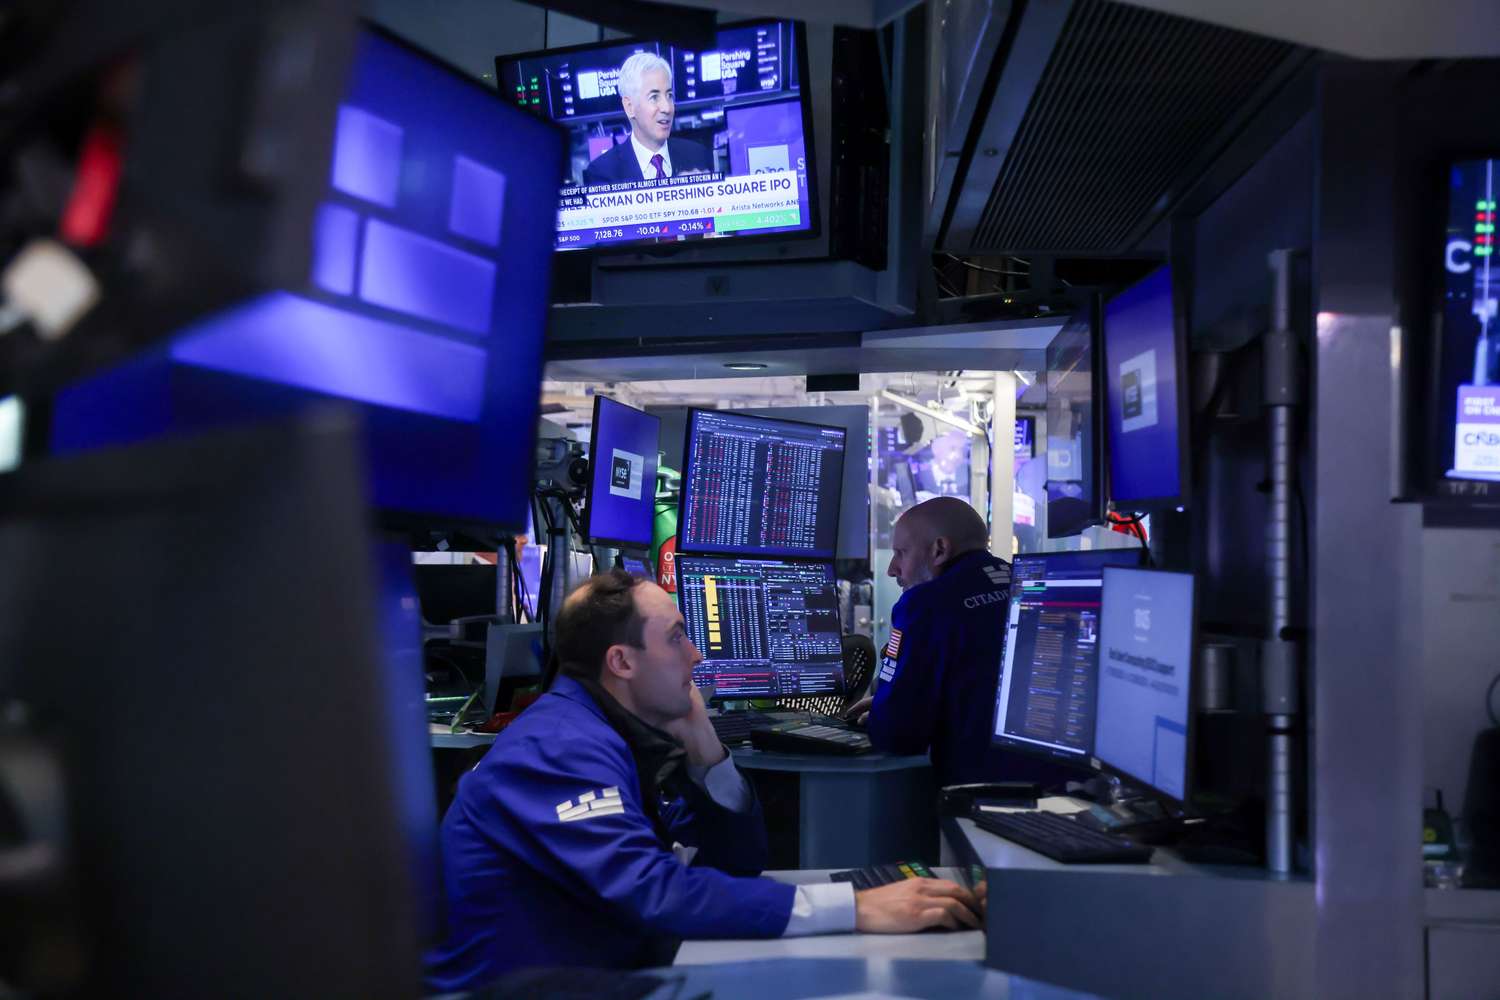
Market Indexes Decline Amid Geopolitical Supply Shocks and Monetary Policy Uncertainty
Major U.S. stock indexes experienced declines, driven by a combination of escalating geopolitical tensions and uncertainty surrounding Federal Reserve policy. The Dow Jones Industrial Average shed 282 points, or 0.6%, while the S&P 500 and Nasdaq Composite also traded lower, down 0.2% and 0.1% respectively. This market reaction occurred despite the Federal Reserve’s decision to hold its key interest rate unchanged. The market’s negative response suggests that rising energy costs and inflationary pressures are overriding the central bank’s signal, highlighting investor sensitivity to external shocks in the current macroeconomic environment.
The Geopolitical Risk Premium: Oil Prices Surge on Iran Blockade
A significant driver of market anxiety was the sharp increase in oil prices. U.S. West Texas Intermediate (WTI) futures gained 7% to trade above $106 per barrel, while the international benchmark Brent crude futures advanced 6% to trade above $118 a barrel. This surge in energy costs introduces a significant inflationary headwind for the global economy.
The escalation follows reports that President Donald Trump instructed aides to prepare for an extended blockade of Iranian ports. The situation intensified after Axios reported that Trump rejected Iran’s proposal to reopen the Strait of Hormuz, stating that the U.S. naval blockade would remain in effect until a deal addressing concerns about Iran’s nuclear program is reached. The Strait of Hormuz, a critical chokepoint for global oil transit, handles a significant portion of the world’s seaborne oil supply. The threat of an extended disruption in this region immediately increases the cost of shipping and insurance, translating directly into higher prices for businesses and consumers worldwide. This decision links energy security directly to geopolitical negotiations, creating a structural risk premium in global energy markets.
Federal Reserve’s Hawkish Hold and Stagflationary Risks
The Federal Reserve’s decision to hold interest rates steady, while potentially intended to provide stability, failed to reassure investors facing escalating inflation risks. The market interpreted this inaction in the face of rising energy costs as a “hawkish hold,” where the central bank acknowledges inflationary pressure but defers action, signaling potential future rate hikes. Federal Reserve Chair Powell explicitly acknowledged the inflationary impact, stating that elevated oil prices “will push up overall inflation” in the near term. This admission highlights the central bank’s challenge in managing inflation driven by supply-side shocks rather than demand-side overheating.
The combination of persistent inflation from energy prices and a potentially constrained central bank creates a stagflationary risk profile. For businesses, higher input costs reduce profit margins, while for consumers, reduced purchasing power dampens demand. The market’s decline reflects a lack of confidence in the ability of current monetary policy to effectively counter these external pressures without triggering a broader economic slowdown.
Sectoral Impact: Boeing and Goldman Sachs Face Macroeconomic Headwinds
The market’s decline was led by specific sectors highly sensitive to the current macroeconomic and geopolitical environment. Boeing and Goldman Sachs were noted as significant contributors to the Dow Jones Industrial Average’s losses. For Boeing, a major aerospace manufacturer, higher oil prices directly impact airline profitability by increasing fuel costs. Airlines, facing reduced margins, may delay new aircraft orders or defer deliveries, impacting Boeing’s revenue forecasts. Geopolitical instability also affects international travel demand and defense spending, adding layers of uncertainty to the company’s operational outlook.
Goldman Sachs, as a major investment bank, is sensitive to market volatility and interest rate expectations. The uncertainty created by rising inflation and a potentially hawkish Fed hold can dampen capital markets activity, including initial public offerings (IPOs) and mergers and acquisitions (M&A). Reduced deal flow and increased market risk aversion directly impact investment banking revenues. The decline in Goldman Sachs’ stock suggests investor concern over the impact of this uncertain environment on financial sector performance.
The Concentration Risk of Big Tech Earnings
The market’s focus now shifts to the upcoming quarterly earnings reports from four of the “Magnificent Seven” trillion-dollar companies. These companies hold significant weight in the S&P 500 and Nasdaq Composite and Nasdaq Composite indexes, meaning their performance dictates the overall direction of the market. The upcoming reports serve as a critical test of whether corporate earnings growth can continue to offset macroeconomic headwinds.
The concentration of market capitalization in a few technology giants creates systemic risk. A strong earnings report could provide a temporary boost to indexes, potentially masking underlying weaknesses in the broader economy. Conversely, a negative surprise could trigger a disproportionate market downturn, given their outsized influence on investor sentiment and index performance. The upcoming reports will provide insight into whether these companies can maintain high growth rates despite rising interest rates and inflationary pressures, determining if the current market decline is a temporary adjustment or the beginning of a broader correction.
Strategic Outlook: Geopolitical Factors Overrule Monetary Policy Assurances
The confluence of geopolitical risk, monetary policy constraints, and corporate earnings uncertainty creates a complex landscape for stakeholders. For corporations, the environment demands careful management of input costs and supply chain resilience. Companies heavily reliant on energy or international shipping face immediate margin pressure. For investors, current dynamics emphasize the importance of diversification beyond concentrated technology holdings and a focus on companies with strong pricing power capable of navigating inflationary pressures.
The market’s immediate reaction suggests that investors are prioritizing geopolitical risk and inflation concerns over central bank assurances. The sustained geopolitical tension in the Middle East ensures that energy prices will remain a primary focus for market participants and policymakers in the near term, complicating the central bank’s policy choices and increasing the risk of a recessionary outcome.
Photo by Pexels on Pixabay.