
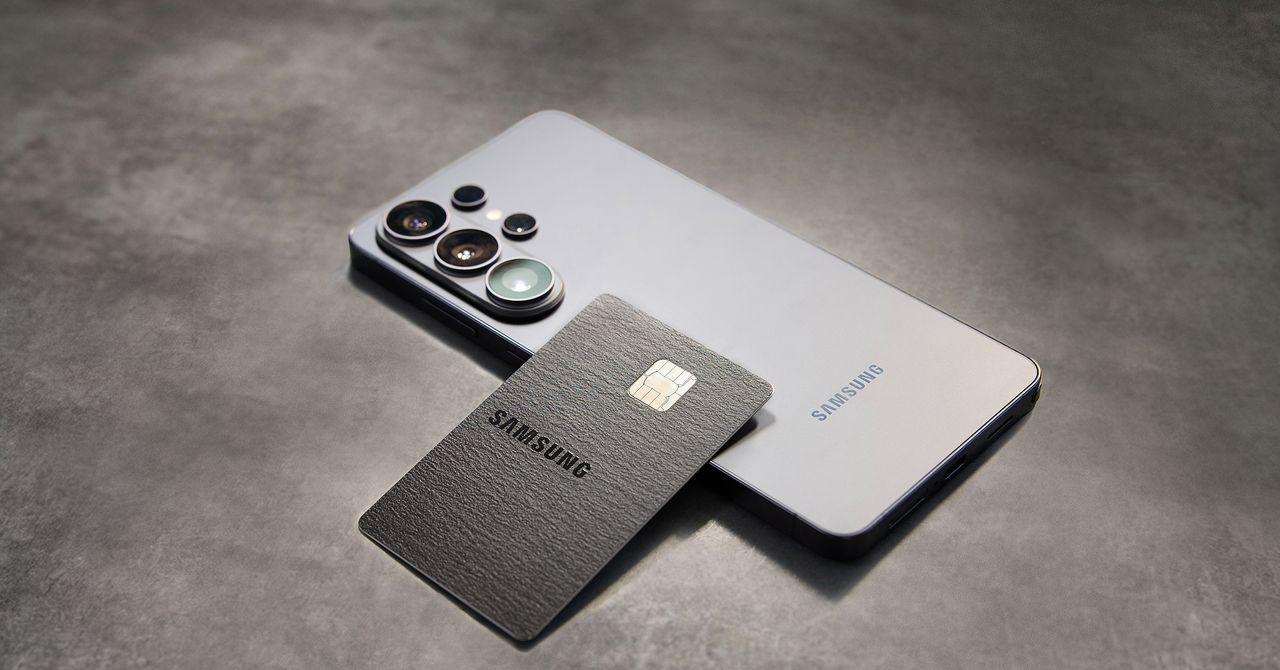
The introduction of the Samsung Galaxy Card signals a sophisticated transition in the conglomerate’s North American strategy, migrating from hardware-centric sales toward the high-margin landscape of integrated financial services. By aligning with Barclays and the Visa network, Samsung is constructing a proprietary financial infrastructure designed to maximize consumer lifetime value and capture critical spending telemetry.
Arriving nearly seven years after the Apple Card, this initiative reflects a calculated response to the complexities of tech-led banking. Positioned strategically ahead of the Galaxy Unpacked event, the card serves as a specialized financing instrument for the high-ticket folding smartphone and wearable segments, effectively lowering the barrier to hardware upgrades through internal credit channels.
Institutional Architecture and Risk Mitigation
Selecting Barclays as the issuing partner represents a prioritized focus on institutional stability. Unlike the volatility seen in competing tech-finance partnerships, Barclays provides a seasoned framework for co-branded credit products and established retail banking infrastructure. This allows Samsung to outsource regulatory compliance and balance-sheet risk while maintaining granular control over the digital user experience.
The utilization of the Visa network ensures immediate global utility and transaction-processing robustness. For Barclays, the partnership offers a high-quality acquisition pipeline, targeting the premium consumer electronics demographic—a segment defined by consistent credit performance and predictable upgrade cycles. This synergy facilitates a low-friction entry into the competitive US credit market.
Reward Engineering and DTC Optimization
The Galaxy Card’s reward tiers are calibrated to prioritize disintermediation. The 5 percent cash reward on direct-to-consumer (DTC) purchases incentivizes users to bypass third-party retailers, allowing Samsung to retain the full retail margin. Simultaneously, the 3 percent reward for Samsung Wallet transactions accelerates the adoption of its proprietary digital payment platform, which functions as the primary gatekeeper for the Galaxy ecosystem.
Lower tiers—2 percent on streaming and 1 percent on general spend—ensure the card remains the primary payment vehicle for recurring daily expenditures. This strategy embeds Samsung’s brand into the user’s monthly financial routine, transforming a cyclical hardware relationship into a continuous service-based engagement.
Materiality, ESG, and Ecosystem Lock-in
The decision to utilize recycled steel for the physical card serves a dual function: it aligns with corporate ESG (Environmental, Social, and Governance) mandates and differentiates the brand from the titanium-heavy aesthetics of competitors. While the physical card acts as a high-status tactile touchpoint, the emphasis remains on the virtual card provisioned within Samsung Wallet, reinforcing a mobile-first philosophy.
The absence of an annual fee is a critical competitive necessity for ecosystem lock-in. By removing entry barriers, Samsung prioritizes market penetration and data acquisition over immediate fee revenue. The resulting data sovereignty allows Samsung to anticipate consumer needs, identifying optimal upgrade windows and tailoring promotional efforts based on real-world spending behavior.
Conclusion: The Data Sovereignty Mandate
Ultimately, the Galaxy Card is less about lending and more about data. The wealth of transaction insights generated allows Samsung to optimize product development and marketing with surgical precision. As the boundaries between technology and finance continue to blur, this move establishes a resilient, service-integrated business model that effectively decouples revenue growth from the volatility of traditional hardware refresh cycles.
Photo by kaboompics on Pixabay.