Unpacking the Structural Drivers of Record Fuel Inflation
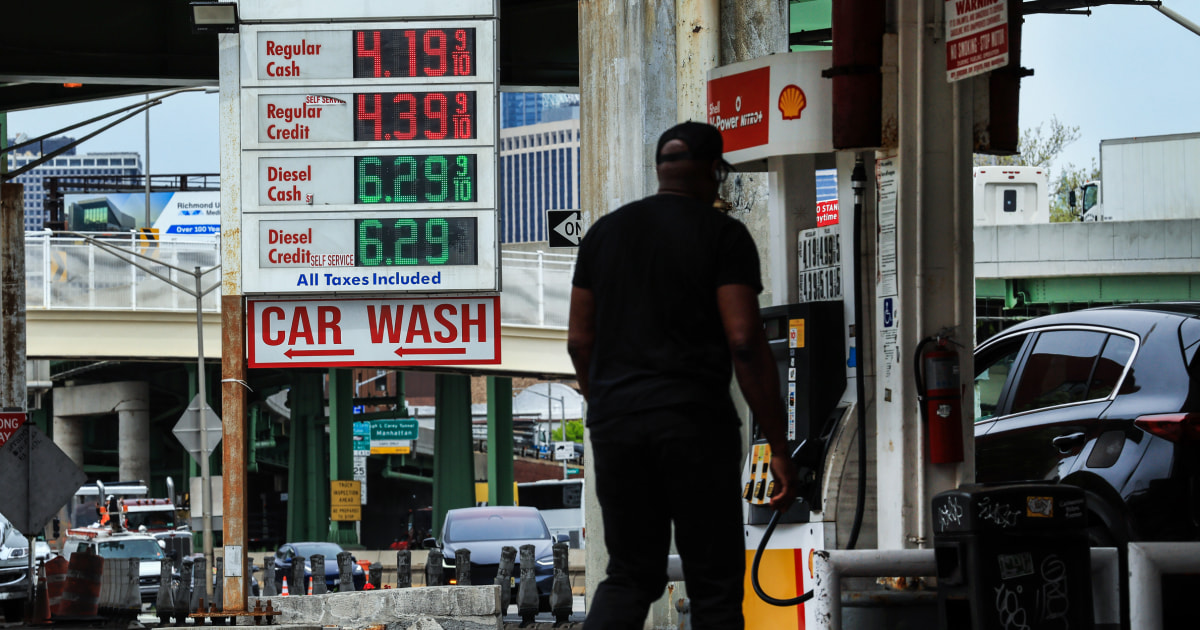
The recent ascent of U.S. gasoline prices to an average of $4.23 per gallon is a confluence of escalating geopolitical instability and critical seasonal industrial constraints. Central to this volatility is the Strait of Hormuz, a vital maritime chokepoint experiencing heightened tensions, significantly disrupting crude oil and petroleum product flows.
Brent crude, the global benchmark, has surged to $114.60, a substantial 25% increase from mid-April lows. This upward trend in global commodity prices directly translates to domestic retail markets, as U.S. gasoline prices are intrinsically linked to the international valuation of crude oil.
Refinery Maintenance and Seasonal Demand Dynamics
Compounding geopolitical pressures, the domestic fuel supply is currently curtailed by scheduled refinery maintenance. This routine operational procedure, coinciding with the transition to the peak spring-summer driving season, inherently tightens supply. This seasonal reduction in output capacity exacerbates the supply-demand imbalance, amplifying the inflationary impact of rising crude costs.
Market analysts highlight that the rapid escalation in retail prices is not solely a product of crude costs but also a consequence of depleted retail margins. For weeks, many retailers absorbed wholesale price increases to maintain prices below the $4 threshold. However, sustained pressure from escalating wholesale costs has necessitated rapid adjustments in consumer-facing prices.
Regional Disparities and Supply Chain Fragility
The situation in Michigan exemplifies how localized market dynamics can amplify national trends. While the national average reached $4.30, Michigan experienced a sharp, isolated spike to $4.58, underscoring the vulnerability of regional distribution networks to refinery outages and localized supply chain bottlenecks.
Michigan’s price volatility, with a 33-cent jump in a single day, illustrates the precarious state of regional fuel inventories. When national benchmarks climb, regional markets with limited access to immediate alternative supply sources often face disproportionately higher price swings as retailers adjust to real-time wholesale cost increases.
Institutional and Economic Ramifications
The current price environment represents a stark departure from the $2.80-$3.15 range observed earlier in the year. This shift signifies a fundamental alteration in the cost structure for both consumers and logistics-dependent industries, impacting operational planning and budget predictability.
The persistence of elevated prices suggests that the market is pricing in a significant risk premium associated with ongoing geopolitical tensions. As long as the Strait of Hormuz remains a focal point of conflict, the potential for further price fluctuations will remain high, irrespective of domestic production levels.
Market Dynamics and Future Projections
The United States’ status as a leading oil producer does not shield its domestic market from global price shocks due to the highly integrated nature of the international crude market. As Brent crude dictates the global benchmark, U.S. gasoline prices remain acutely susceptible to international supply disruptions, even with robust domestic extraction.
Energy sector stakeholders are currently navigating a landscape characterized by rapid price adjustments and the exhaustion of conventional buffer mechanisms. Market stabilization hinges on the de-escalation of tensions affecting the Strait of Hormuz and the successful conclusion of seasonal refinery maintenance cycles.