The emergence of a ‘Super El Niño,’ potentially the most intense thermal event in 150 years, necessitates a recalibration of global risk frameworks. Data from Berkeley Earth indicates a 90% probability that tropical Pacific temperatures will exceed all historical benchmarks since 1850, creating a period of sustained atmospheric instability extending into late 2026.
This thermal anomaly is not a transient seasonal shift but a systemic disruption. The World Meteorological Organization (WMO) confirms that the pattern, established in mid-2023, will exert maximum pressure on infrastructure, energy grids, and agricultural output during the 2024-2025 winter peak and beyond.
Macroeconomic Asymmetry: Regional Economic Divergence
The Super El Niño cycle introduces a stark economic divergence across North America, characterized by asymmetric supply and demand shocks. In the northern United States and Canada, projected milder winters typically reduce residential heating demand, placing downward pressure on natural gas prices and utility revenue streams. Conversely, the southern tier faces heightened flood risks and severe convective storms.
For the agricultural sector, increased precipitation in the South can disrupt winter produce cycles and logistics, while the North may see extended growing windows or altered soil moisture profiles. These shifts require proactive inventory positioning and supply chain diversification to mitigate localized disruptions in the commodity markets.
Infrastructure Integrity and Coastal Asset Devaluation
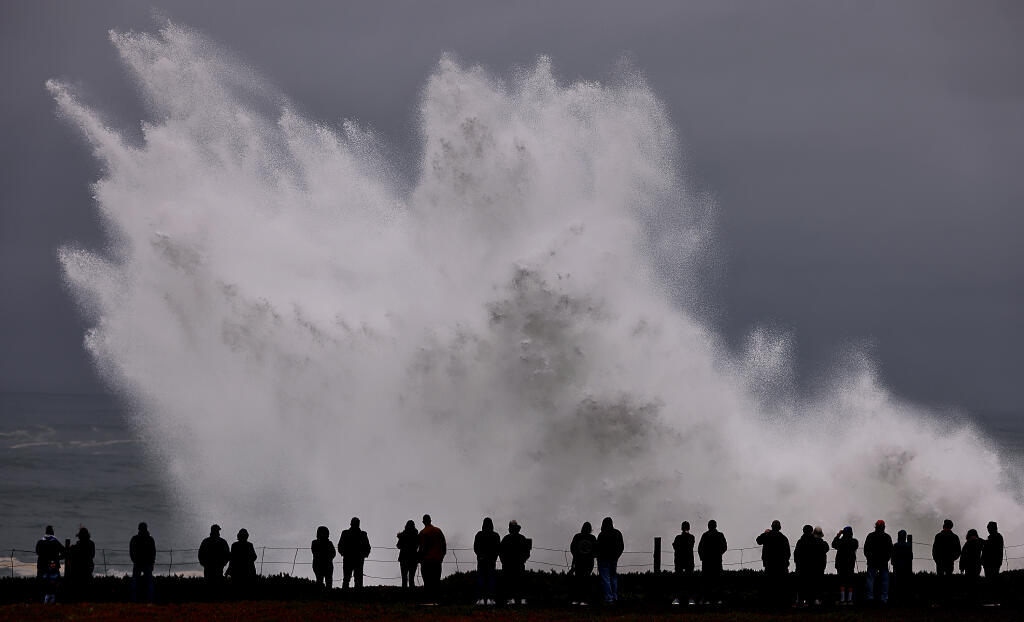
Coastal regions, particularly Northern California, face compounding vulnerabilities. Senator Mike McGuire and climate scientists like Daniel Swain have highlighted the convergence of record-high sea levels and increased storm frequency. This is not merely an environmental concern but a fiscal one: the combination of thermal expansion and storm surges threatens to accelerate coastal erosion and overwhelm existing drainage systems.
Municipalities face rising liabilities regarding public infrastructure, including sewage and transportation networks. The necessity for ‘extraordinary’ shoreline management suggests a massive reallocation of state and federal capital toward asset protection. Real estate valuations in high-risk coastal zones may face downward pressure as insurance premiums adjust to the reality of multi-year erosion cycles.
Market Mitigants: The Atlantic Buffer and Reinsurance Dynamics
A significant counter-balance to Pacific volatility is the typical suppression of Atlantic hurricane activity during El Niño phases. This vertical wind shear provides a strategic ‘breathing room’ for the property and casualty insurance sectors to stabilize reserves following previous high-loss years. However, this relief is often offset by the increased frequency of atmospheric river events on the West Coast.
Institutional investors are increasingly treating these multi-year ENSO (El Niño-Southern Oscillation) cycles as material risks. The long-term persistence of this event through 2026 complicates capital planning for infrastructure projects, as the cumulative effect of repeated extreme weather events can lead to structural fatigue and accelerated depreciation of public works.
Strategic Policy and Operational Resilience
The integration of real-time meteorological data into public policy—exemplified by legislative town halls and expert panels—is becoming a critical component of economic stability. By providing actionable data, officials aim to reduce the ‘economic friction’ caused by reactive decision-making and misinformation.
Ultimately, the 2024-2026 Super El Niño serves as a stress test for global resilience. Success will be measured by the ability of state agencies and private enterprises to translate complex ocean temperature anomalies into granular risk mitigation strategies. The lessons learned during this thermal cycle will likely dictate infrastructure and capital allocation priorities for the next decade.