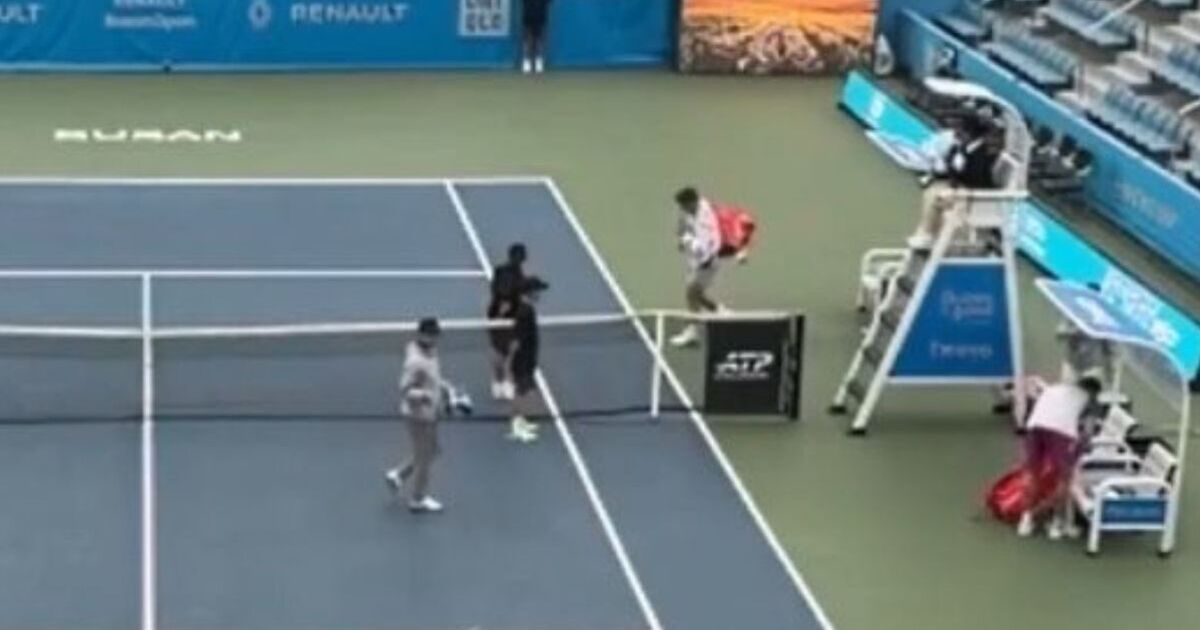
The weather-induced suspension of Liam Broady’s quarter-final match at the Busan Challenger introduces a critical operational bottleneck for the British player. Maintaining a seven-match winning streak, Broady secured the opening set 6-3 against August Holmgren before play was halted at 0-1 in the second. This interruption forces a condensed schedule, mandating that the victor navigate two high-intensity matches within a single afternoon, including a semi-final against Leandro Riedi. For athletes returning from injury, this compression escalates the risk of physical attrition and tests the efficacy of immediate recovery protocols.
The Economics of the Challenger Circuit: Resilience as a Commodity
Ranked outside the top 200 following an injury-forced hiatus, Broady’s strategic prioritization of the Asian swing—evidenced by his Miyazaki title—is a calculated effort to recapture top-100 status. The Busan delay transcends mere logistical inconvenience; it represents a structural risk inherent in the lower-tier professional circuit. Unlike the ATP primary tour, where facility infrastructure often mitigates weather impact, the Challenger Tour demands a high degree of environmental adaptability. Broady’s technical efficiency, demonstrated by his 45-minute routing of Murphy Cassone, suggests a capacity to manage double-headers, yet the cumulative fatigue of back-to-back matches remains a significant performance variable.
Bridging Performance Volatility and Prediction Markets
Parallel to the physical contingencies in Busan is the maturation of decentralized prediction markets. These platforms have evolved from niche speculative tools into sophisticated financial instruments that commodify uncertainty. By trading shares in specific outcomes—be it a match result or a central bank rate adjustment—participants engage in a real-time price discovery mechanism. A ‘Yes’ share trading at $0.65 represents a 65% aggregate market probability, providing a more reactive and capital-backed data set than traditional polling or static sportsbooks.
Institutional Integration and Risk Hedging
The surge in prediction market volume is underpinned by the integration of crypto-native liquidity, which bypasses traditional intermediary friction. Traders increasingly utilize these markets to hedge against exogenous shocks. In the context of the Busan suspension, the sudden shift in scheduling creates an immediate information asymmetry that prediction markets are uniquely equipped to price. As weather conditions impact player fatigue and win probabilities, share prices recalibrate instantaneously, offering a transparent benchmark for situational risk that traditional betting markets often struggle to match with equal granularity.
Oracles and the Future of Probability Trading
The integrity of these markets relies on decentralized oracles to ensure immutable settlement based on verified event data. This technological layer eliminates the counterparty risk associated with centralized authorities, facilitating the expansion of markets into virtually any verifiable domain. As information continues to be commodified, the distinction between sports wagering and institutional risk management blurs. Whether managing the physical toll of a rescheduled tennis match or hedging against BTC price volatility, the underlying objective remains the same: the efficient conversion of probability into actionable capital allocation.