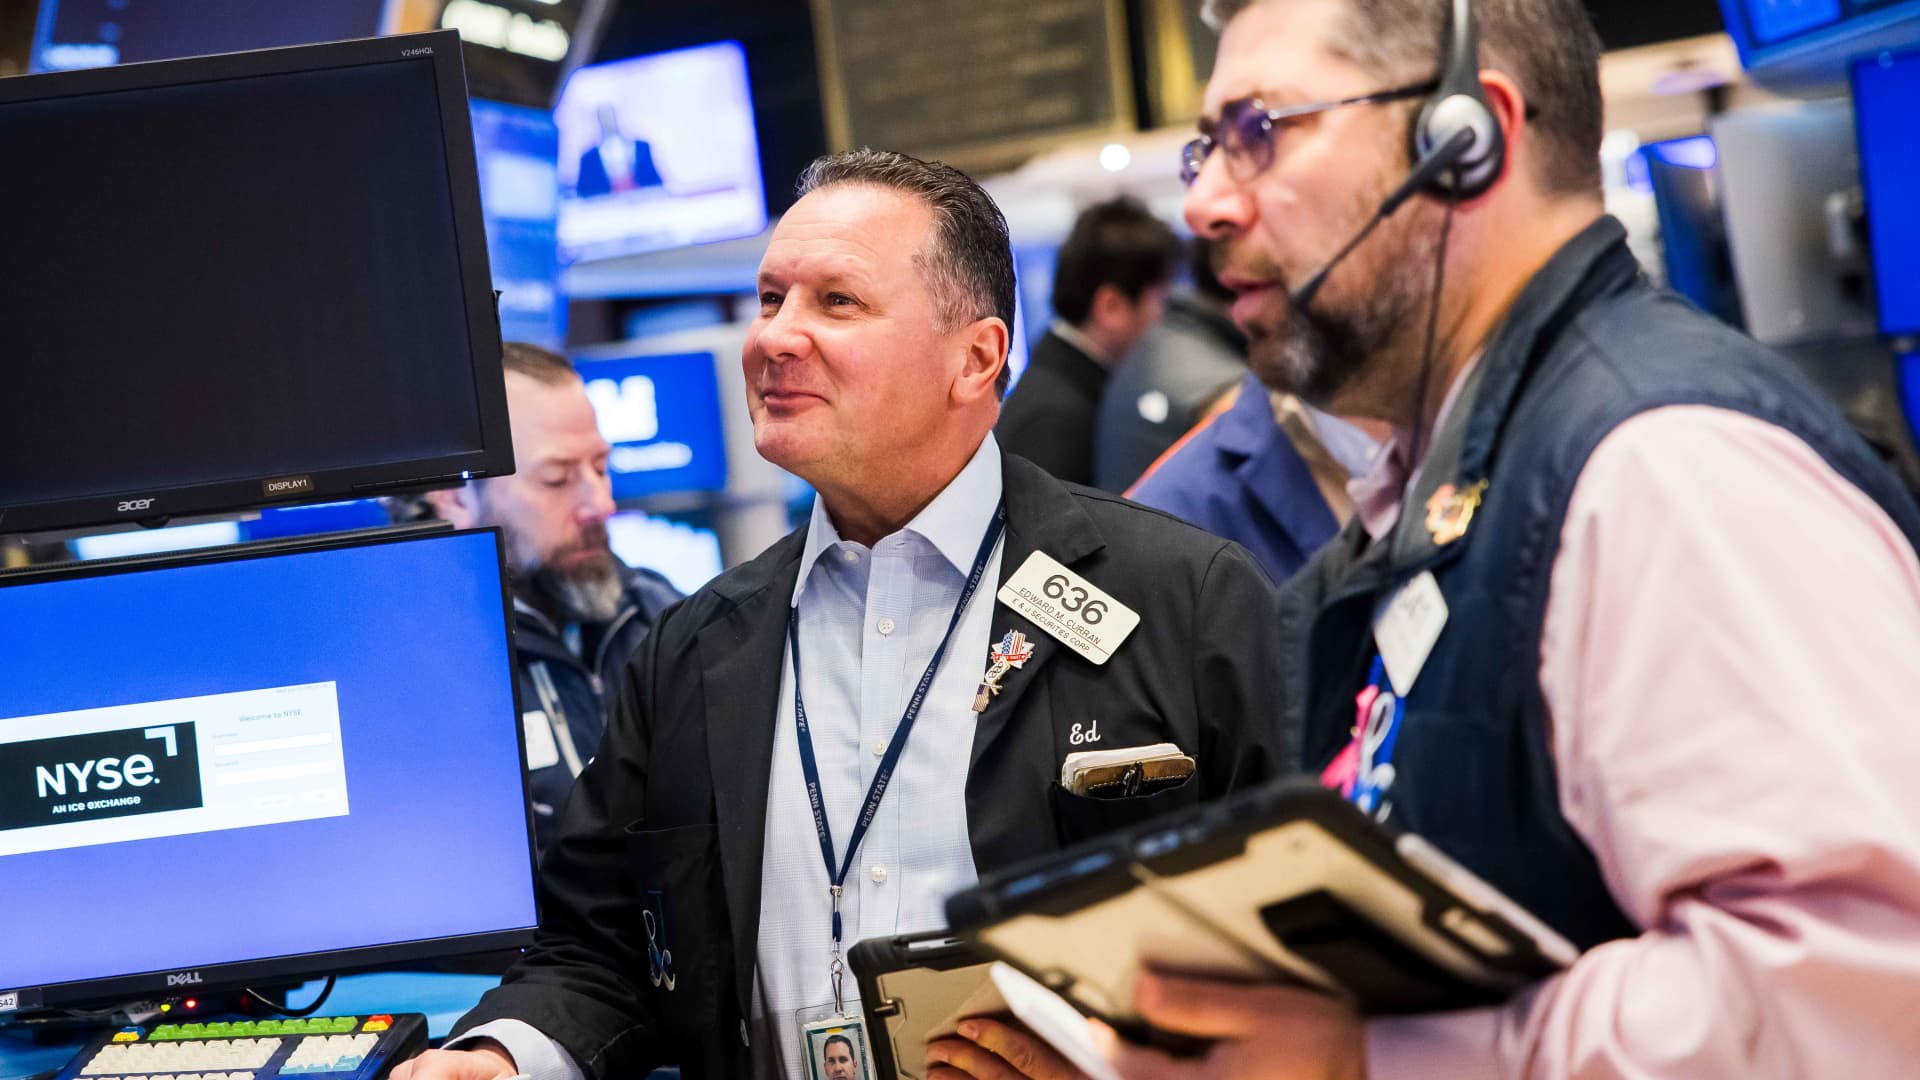
The divergence in U.S. equity markets on Wednesday highlighted a critical recalibration of institutional risk, as capital migrated from high-expenditure tech integration toward industrial stability. While the Dow Jones Industrial Average rose 0.49% to a record 54,349.12, the broader indices grappled with the fiscal implications of high-velocity AI infrastructure spending. This decoupling underscores a growing market distinction between AI hardware providers and the firms absorbing massive operational costs to integrate these technologies.
Fiscal Scrutiny and the SpaceX CapEx Paradox
SpaceX’s inaugural quarterly report since its June IPO catalyzed a 13% share price contraction, exposing the friction between private-market growth narratives and public-market transparency. The company reported a sixfold surge in capital expenditures to $18.4 billion for Q2, far exceeding analyst expectations. This aggressive deployment signals a pivot from aerospace logistics to a data-centric AI model, though the immediate result is valuation compression as investors weigh long-term dominance against immediate margin erosion.
Market skepticism regarding the AI ROI timeline is intensifying. For SpaceX, the financial pressure is compounded by an impending 20% share unlock event. This liquidity surge, arriving amidst a post-earnings slump, is expected to exert further downward pressure as institutional insiders potentially seek to realize gains, testing the stock’s support levels in a volatile environment.
Nvidia’s Infrastructure Hegemony
Contrasting the SpaceX decline, Nvidia shares gained over 3% following Elon Musk’s confirmation of SpaceX’s exclusive reliance on Nvidia silicon. This partnership solidifies Nvidia’s status as the indispensable utility of the AI era, effectively transferring operational and capital risk to the customer. By securing a single-vendor ecosystem, Nvidia maintains high-margin revenue while creating a prohibitively expensive switching cost for SpaceX.
This exclusivity creates a significant competitive bottleneck for rivals like AMD. While AMD reported an earnings beat, its stock fell—a phenomenon dubbed the ‘exceptionalism trap.’ In the current climate, meeting targets is insufficient; only total market capture or unprecedented margin expansion can justify current price-to-earnings multiples. This dynamic contributed to the Nasdaq’s 0.83% retreat as risk concentration in the semiconductor sector became more pronounced.
Geopolitical Tailwinds and the Dow’s Record Performance
The Dow’s record-breaking climb was bolstered by diplomatic progress in the Strait of Hormuz. President Trump’s indication of a potential deal to reopen this vital maritime corridor provided a tailwind for industrial and energy sectors. The prospect of stabilized global supply chains and reduced inflationary pressure triggered a tactical reallocation, with investors seeking shelter in Dow-weighted industrials that offer predictable cash flows compared to the volatility of AI-heavy tech firms.
The Maturation of the AI Trade
The S&P 500’s retreat from its own record high suggests that the ‘Magnificent Seven’ are no longer moving in unison. Instead, a granular assessment of capital efficiency is taking precedence. The market is increasingly demanding proof of operational utility from AI investments rather than mere announcements of spending. As the cycle matures, the advantage remains with hardware providers like Nvidia, while implementers face a more skeptical investor base focused on Return on Invested Capital (ROIC).