Executive Action Establishes $1.8 Billion Federal Fund Amidst Controversy
The Trump administration’s establishment of the nearly $1.8 billion ‘Anti-Weaponization Fund,’ intended to compensate individuals alleging unfair targeting by prior administrations, directly stems from a controversial settlement between the Internal Revenue Service (IRS), Donald Trump, his adult son, and the Trump Organization.
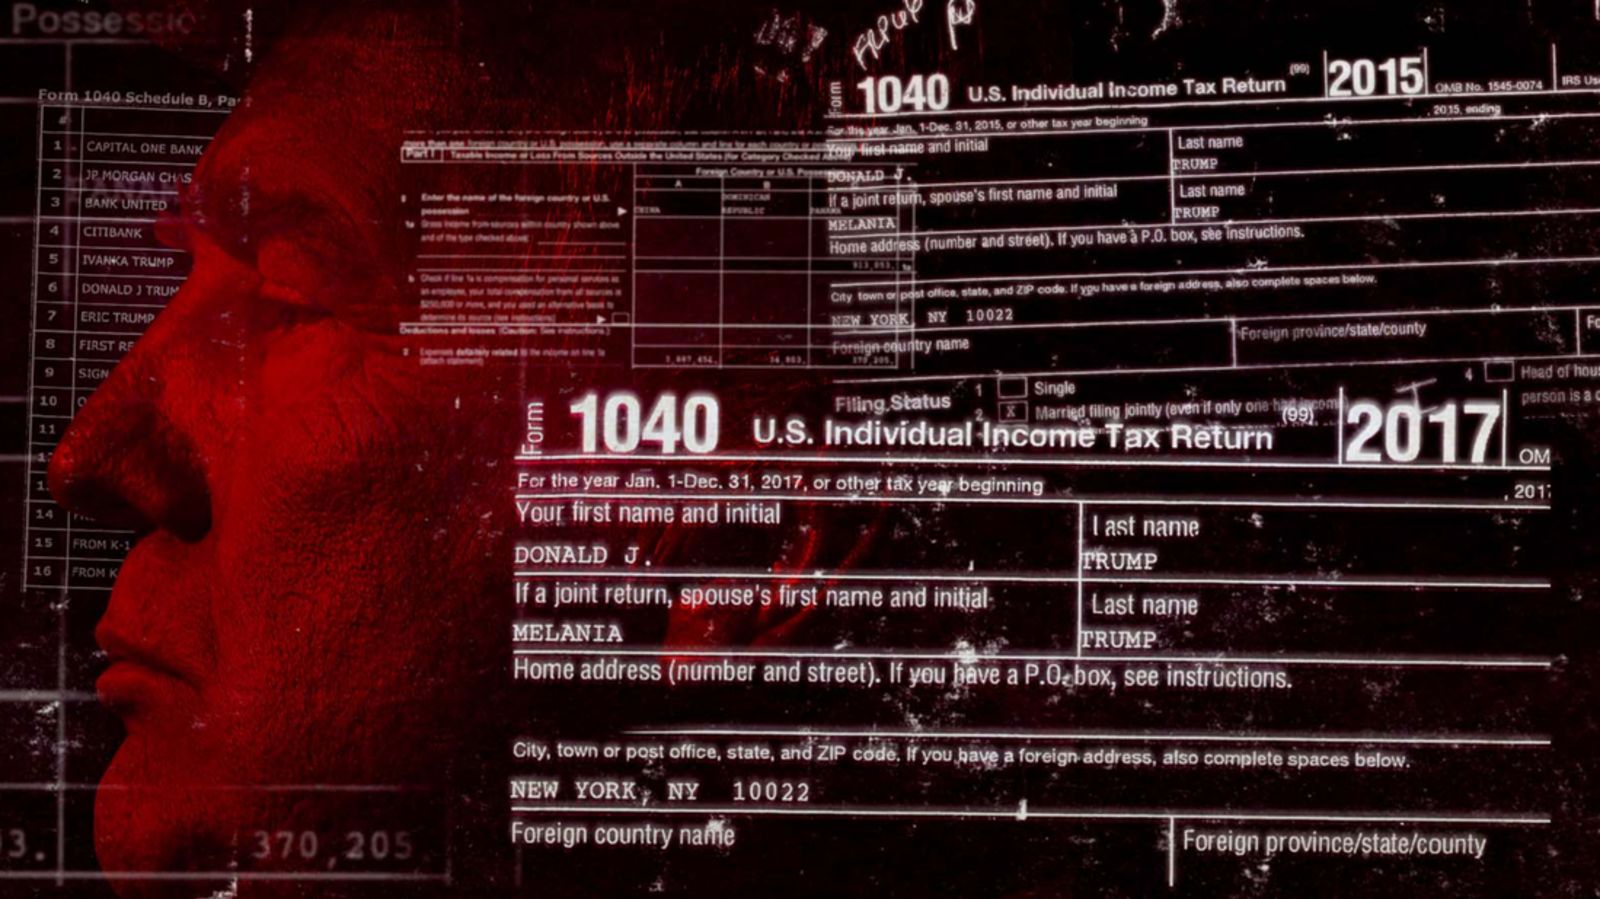
Originating from a lawsuit filed by Trump in January over unauthorized tax information disclosure, the settlement uniquely mandated this fund’s creation and included a crucial federal concession: an agreement to forgo future claims against Trump, his family, or businesses for past tax-related matters. This dual outcome immediately raised questions regarding accountability and judicial precedent.
Operational Ambiguity and Fiscal Implications of the Anti-Weaponization Fund
The fund’s operational framework for identifying and compensating ‘unfairly targeted’ individuals remains profoundly ambiguous, prompting immediate scrutiny over disbursement criteria and oversight mechanisms. Critics have swiftly decried it as a potential ‘slush fund’ for political allies, directly challenging its transparency, impartiality, and the integrity of its application.
Such a substantial $1.8 billion allocation diverts significant federal resources, raising profound concerns about fiscal responsibility and opportunity cost. The inherent ambiguity of ‘unfair targeting’ for claim validation and adjudication poses considerable administrative challenges, ripe for discretionary application rather than objective assessment.
Beyond direct outlay, the fund’s existence influences public perception of federal spending priorities, particularly the allocation of taxpayer funds. Directing this sum based on subjective grievances rather than established legal or social welfare criteria establishes a novel and potentially problematic precedent in federal resource management.
This novel mechanism inherently creates a political incentive structure, potentially rewarding loyalty or perceived alignment with the administration’s narrative, thus distorting the traditional flow of federal compensation and resource allocation.
Strategic Concessions and Regulatory Precedent in the IRS Settlement
The settlement’s provision granting immunity from future federal claims against Trump, his family, and businesses for past tax issues represents a profoundly strategic and unprecedented concession. This effectively shields specific entities from the very federal apparatus—the IRS—responsible for tax enforcement, compromising its perceived independence.
This agreement establishes a complex regulatory precedent, potentially influencing future federal agency settlements with high-profile political figures. It fundamentally questions the independence of federal enforcement bodies and the consistent application of tax law, eroding public trust in impartial governance.
For the IRS, these implications are considerable; the settlement could undermine its enforcement authority and impartiality. This perception might adversely affect compliance rates and the agency’s long-term operational effectiveness, particularly concerning its ability to operate free from political influence.
This aspect of the settlement also carries significant competitive implications, particularly for businesses and individuals who do not possess similar political leverage. The perceived unequal application of legal and regulatory standards can distort market fairness and create an uneven playing field.
Legal Challenges and Institutional Friction
The fund’s legality and implementation are already facing immediate judicial challenges, with at least one lawsuit filed seeking to halt its operation. Legal experts consulted by CNN remain divided on the potential for these challenges to successfully impede the fund, highlighting the unprecedented nature of its creation.
This legal uncertainty underscores the inherent institutional friction, pitting executive action against judicial oversight and public interest litigation. The outcomes will significantly delineate the boundaries of executive power in resource allocation and settlement agreements, particularly concerning broad public interest implications.
The judicial process will scrutinize the fund’s constitutional basis, the scope of executive authority in settling lawsuits with such wide-ranging implications, and the potential for abuse of discretion—a critical test for the checks and balances governing federal actions.
The divided expert opinion reflects the profound novelty and complexity of the legal questions, particularly regarding the undefined scope of ‘weaponization’ and the mechanisms for redress. The clear absence of legal precedent significantly complicates judicial review and potential rulings.
Political Incentives and Stakeholder Exposure
The fund’s establishment has already ignited a ‘GOP civil war,’ exposing deep divisions within the Republican party over its propriety and broader implications. This internal conflict underscores strategic political calculations and varied stakeholder alignments.
Georgia Representative Andrew Clyde’s public endorsement, coupled with his personal interest in seeking compensation due to past IRS entanglement (despite a prior substantial refund), exemplifies the direct political incentives. This positioning frames him as both a potential beneficiary and a vocal advocate for the fund’s stated purpose, further blurring lines between public service and personal gain.
This alignment extends to a broader group, including individuals involved in the January 6 events and other Trump allies, reportedly considering payouts. This dynamic reveals the fund’s potential as a mechanism for solidifying political alliances and overtly rewarding perceived loyalty.
Taxpayers face significant exposure as federal funds are directed towards a program whose criteria and beneficiaries are subject to intense political and legal debate. The notable absence of explicit legislative approval for such a substantial fund critically questions democratic accountability and oversight mechanisms.
The implications for the media landscape are also pronounced, with the fund becoming a focal point for narratives concerning political corruption, executive overreach, and the weaponization of government agencies. This shapes public discourse and influences voter perception of governmental integrity.
Broader Institutional and Governance Implications
The settlement, explicitly reached by Trump and the Executive Branch under his direct control, underscores the vast power vested in the presidency to negotiate with federal agencies. This concentration of authority in sensitive tax enforcement raises critical concerns about potential conflicts of interest and the erosion of institutional independence and impartiality.
The creation of a fund to address perceived ‘weaponization’ by ‘previous administrations’ frames the issue within a broader historical context of political grievances and partisan conflict. It institutionalizes a narrative of governmental abuse, potentially deepening societal divisions and distrust in federal institutions.
The persistent absence of clear, universally accepted definitions for ‘unfair targeting’ or ‘government weaponization’ leaves the fund’s administration acutely vulnerable to accusations of political bias and arbitrary decision-making, significantly challenging objective oversight and accountability.
The long-term consequences for governance could include a precedent where executive settlements become tools for political patronage or for insulating specific individuals from legal scrutiny. This would fundamentally alter the balance of power between the executive, legislative, and judicial branches.
The controversy surrounding the fund and settlement highlights the ongoing tension between political expediency and the fundamental principles of impartial justice and administrative fairness. The resolution of these multifaceted challenges will profoundly affect the operational integrity of federal agencies and public confidence in governmental processes.
Ultimately, the ‘Anti-Weaponization Fund’ and its foundational settlement represent a complex interplay of legal maneuvering, political strategy, and fiscal allocation. Its unfolding implications will continue to be a critical barometer for the state of institutional checks and balances and the future trajectory of federal governance.