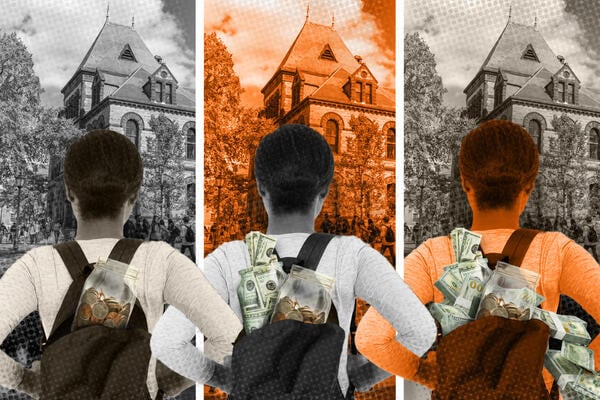
The July 1st Pivot: Structural Realignment of Federal Credit
The activation of the One Big Beautiful Bill Act on July 1 initiates a fundamental transition in the federal government’s role as a primary creditor. This overhaul replaces a broad-access lending model with a performance-driven credit market, prioritizing institutional accountability and the mitigation of taxpayer liability. By implementing tiered repayment structures and stringent loan limits, the administration is executing a strategic retreat from the expansive, uncapped lending policies that characterized previous decades.
For the 43 million borrowers holding $1.7 trillion in federal debt, this recalibration alters the long-term cost of capital for personal advancement. The Department of Education’s implementation of ‘commonsense loan limits’ specifically targets the graduate and professional sectors—historically the primary drivers of debt accumulation. This shift necessitates a market-wide reassessment of the value proposition offered by higher education institutions, particularly those whose operational budgets rely heavily on federal subsidies.
The Earnings Test: A New Metric for Institutional Viability
At the core of this regulatory framework is a rigorous accountability measure linking program access to graduate outcomes. Undergraduate programs must now demonstrate that alumni earnings exceed the median income of high school graduates within the same cohort. This earnings test introduces a competitive floor, effectively de-authorizing programs that fail to provide a measurable return on investment (ROI).
The 641-page final rule establishes a high-stakes environment for university administrators: programs failing the test in two out of three consecutive years face a mandatory two-year suspension from the federal loan system. For graduate programs, the benchmark is elevated, requiring salaries to surpass those of bachelor’s degree holders. This structural pressure is intended to prune the federal portfolio of high-risk, low-reward programs identified by the House Education and Workforce Committee as detrimental to student financial health.
Strategic Implications for Graduate and Professional Education
Tightened caps on professional and graduate borrowing fundamentally disrupt the enrollment economics of advanced degrees. Historically, these programs served as high-margin revenue drivers for universities, subsidized by uncapped federal liquidity. The new ceilings force institutions to either secure alternative funding mechanisms or rationalize tuition rates to align with restricted borrowing capacity.
A notable exception exists for the nursing profession, which secured a ‘professional’ loan designation following a strategic judicial ruling. This status provides a comparative advantage, allowing nursing programs to navigate the new limits with greater flexibility than other graduate tracks. Such carve-outs highlight the emerging legal and administrative friction as various sectors compete to maintain access to federal capital under more restrictive standards.
Repayment Restructuring and Amortization Acceleration
The transition to a tiered standard repayment system introduces immediate cash-flow implications for lower-income borrowers. While the Department of Education frames this as a move toward a ‘healthier lending system,’ the change increases the monthly debt service burden for those with limited financial flexibility. This aligns with a broader policy objective: reducing federal exposure to non-performing debt and long-term subsidies.
By adjusting monthly payment thresholds, the administration aims to accelerate the amortization of the $1.7 trillion portfolio. This strategy reflects Education Secretary Linda McMahon’s mission to minimize the department’s operational footprint and limit public liability. The intent is to transition toward a system where the borrower, rather than the taxpayer, bears the primary financial risk of educational investment.
Parental Borrowing and Macro-Level Inflation Controls
The contraction of parental credit through tighter borrowing caps represents a significant shift in family-based education financing. With federal liquidity restricted, households must become more price-sensitive, which serves as a macro-level control on tuition inflation. As families are forced to prioritize institutional value over prestige, universities face increased pressure to optimize operational costs or risk declining enrollment from middle-income demographics.
Administrative Philosophy and Systemic Risk Management
The overhaul is a central pillar of the Working Families Tax Cuts Act and broader executive actions aimed at decentralizing federal education oversight. By tightening loan issuance criteria, the administration is effectively downsizing the Department of Education’s financial liability. Rep. Tim Walberg’s stance—that taxpayer funds should not subsidize underperforming programs—underscores the transition from education as an entitlement to education as a strategic investment.
The success of this $1.7 trillion portfolio management strategy depends on the labor market’s capacity to absorb graduates into high-earning roles. While the 641-page rule provides a compliance roadmap, the four-year lag in earnings data creates a period of strategic uncertainty. Institutions must now proactively align curricula with market demand to ensure long-term solvency in an era of performance-contingent federal funding.