FCC Abolishes 39% TV Ownership Cap, Igniting Broadcast Media Consolidation
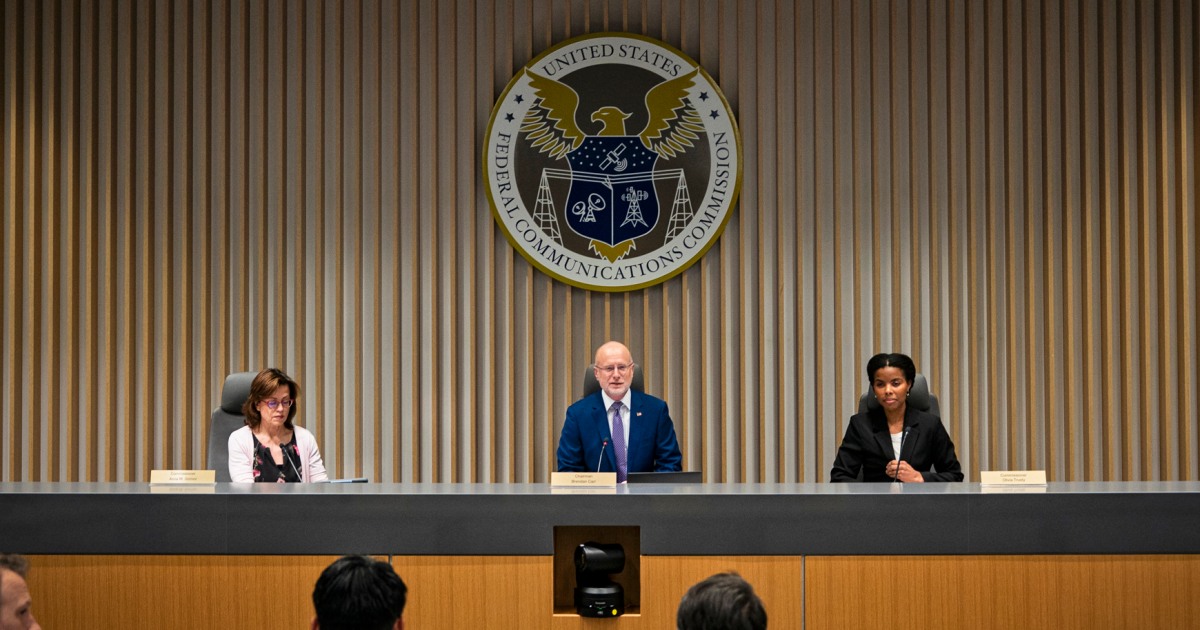
The Federal Communications Commission (FCC) has enacted a significant policy reversal, voting along party lines to eliminate the 39% national TV household ownership cap. This long-standing rule previously restricted any single company from owning television stations collectively reaching more than 39% of all U.S. TV households. This decision marks a pivotal moment for the broadcasting sector, removing a decades-old structural constraint and fundamentally reshaping the media landscape.
This regulatory shift is a substantial victory for major media conglomerates, particularly those with conservative leanings like Sinclair Broadcast Group and Nexstar, which have actively lobbied for its repeal to broaden their national footprint. These immediate beneficiaries are now poised to leverage newfound flexibility for aggressive growth strategies, fundamentally altering the competitive dynamics of the U.S. television market.
Policy Rationale and Strategic Reorientation
The FCC’s media bureau asserted that the 39% cap had become an **anachronism** in the contemporary media environment. Commissioners argued that the regulation, rather than fostering competition, actively constrained local television networks from achieving the necessary scale to effectively compete against evolving digital platforms and national content distributors. This perspective posits that such constraints hindered investment and innovation essential for broadcast viability.
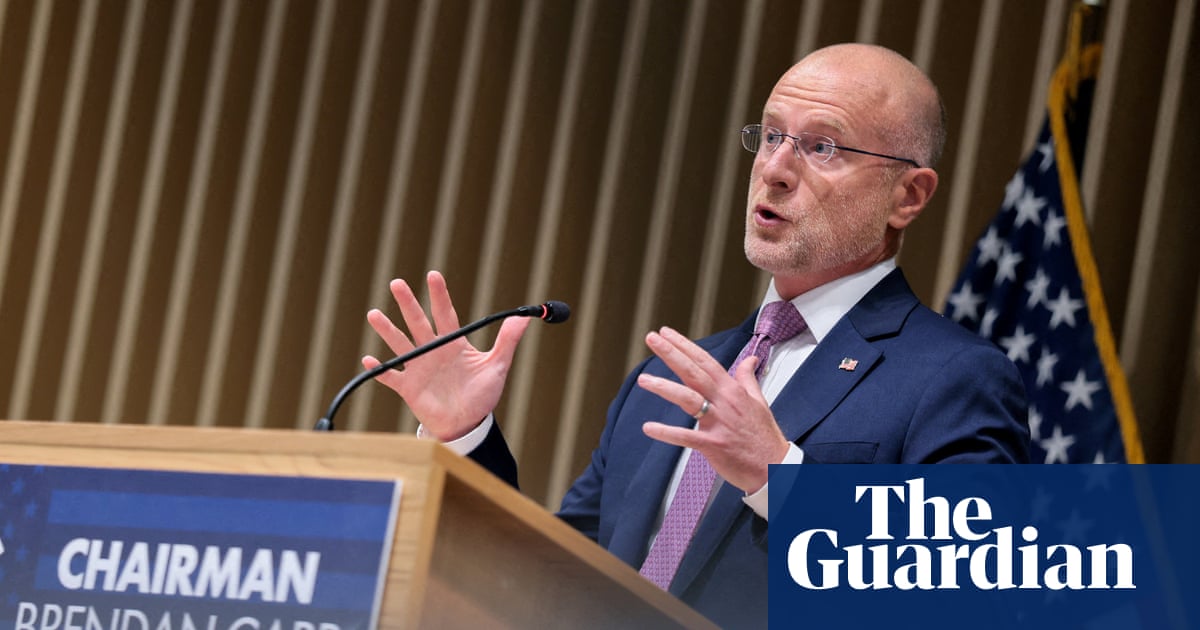
FCC Chair Brendan Carr, along with Trump-appointed Commissioner Olivia Trusty, championed the repeal as a crucial step to bolster broadcasters. They framed the deregulation as vital for traditional television outlets to adapt to a rapidly evolving media ecosystem, citing fragmented audiences and diverse content consumption habits. While not a panacea, the repeal was presented as necessary for sustained competitiveness against new media entrants.
Carr further posited that the repeal would ultimately benefit local broadcasters, despite the immediate advantages accruing to large media conglomerates. This argument rests on the premise that increased scale at the top tier would generate operational efficiencies and enhanced resource access, theoretically strengthening local operations through a trickle-down effect. However, the direct mechanisms for this proposed benefit remain contingent on complex market forces and corporate strategies.
The shift from a rigid 39% ownership limit to a more flexible case-by-case review approach signifies a fundamental philosophical change in regulatory oversight. This departure from prescriptive, quantitative thresholds introduces significant **discretion** into merger and acquisition approvals. While offering greater latitude for strategic maneuvering, this also increases regulatory uncertainty for market participants, requiring more intensive and potentially politicized lobbying efforts for expansion.
Market Concentration and Competitive Dynamics
The 39% cap, initially established at 35% in the 1990s and raised by Congress in 2004, was specifically designed to mitigate excessive media ownership concentration and foster a diversity of voices. Its repeal therefore marks a significant departure from this long-held regulatory principle, directly facilitating **unprecedented market consolidation** within the broadcast television sector.
For major players such as Sinclair and Nexstar, the removal of this ceiling unlocks substantial strategic opportunities. These corporations can now pursue acquisitions of additional stations unconstrained by national reach limits, fostering a more concentrated ownership structure across numerous local markets. This expansion is projected to yield significant economies of scale in content production, advertising sales, and operational overhead, enhancing their market dominance.
A larger portfolio of stations inherently enhances bargaining power with cable and satellite distributors and national advertisers. This increased leverage can secure more favorable carriage agreements and higher advertising rates, directly boosting revenue streams and profitability for consolidating entities. Conversely, this raises profound concerns about adverse competitive impacts on smaller, independent broadcasters, who may struggle to compete.
Smaller market participants, lacking the scale and financial resources of their larger counterparts, face an increasingly challenging competitive landscape. This dynamic is likely to accelerate the acquisition of independent stations, further diminishing diversity of ownership and potentially narrowing the range of local news and programming perspectives available to viewers. Such consolidation risks homogenization of content and reduced accountability.
Proponents assert that increased scale enables larger entities to invest more significantly in technology, content, and infrastructure, theoretically improving the quality and reach of local broadcasting. This argument implicitly suggests that the economic benefits of scale supersede the risks of market concentration. Critics, however, frequently contend that such consolidation often leads to centralized news production, reduced newsroom staffing, and a diminished emphasis on truly local content, thereby eroding community-specific reporting.
The historical context of the 39% cap underscores a persistent tension between fostering market efficiency through scale and safeguarding public interest values such as localism and viewpoint diversity. The FCC’s decision represents a contemporary re-evaluation of this regulatory balance, distinctly prioritizing the economic viability and competitive positioning of traditional broadcasters amidst a rapidly fragmented media landscape.
Operational and Financial Implications
Operationally, eliminating the ownership cap facilitates greater integration and synergy across expanded station networks. Companies can now centralize functions like content acquisition, programming scheduling, and back-office operations, leading to substantial cost efficiencies and streamlined workflows. This freed-up capital can be reinvested or contribute to enhanced profitability, optimizing resource allocation previously constrained by disparate structures.
Financially, the expanded national reach potential makes broadcast assets significantly more attractive for investment and acquisition. This is likely to exert upward pressure on valuations of television station groups as the pool of nationally ambitious buyers grows. While this presents monetization opportunities for existing owners, it simultaneously raises the barrier to entry for new, smaller market entrants, exacerbating concentration.
Increased scale also provides a robust platform for negotiating with national advertisers, who seek broad demographic reach and simplified ad buying. A consolidated entity presents a more compelling value proposition, potentially capturing a larger share of national advertising spend and substantially strengthening its financial position relative to less integrated competitors. This enhanced leverage impacts the broader advertising market.
However, aggressive pursuit of scale through acquisitions carries inherent capital expenditure and integration risks. Companies undertaking such expansion must navigate complex regulatory approvals, integrate diverse corporate cultures, and ensure anticipated synergies materialize without compromising local market relevance or viewer loyalty. The substantial financial leverage typically required for large-scale M&A activity also introduces critical balance sheet considerations and potential debt burdens.
The shift to case-by-case review, despite its flexibility, introduces regulatory unpredictability that significantly influences investment decisions. Companies must now account for the subjective nature of future FCC reviews, potentially impacting deal timelines, transaction certainty, investor confidence, and overall capital allocation strategies within the sector.
Political Context and Institutional Response
The FCC’s party-line vote starkly underscores the highly politicized nature of media regulation in the United States. Support from Trump-appointed commissioners, including Chairman Carr, highlights an alignment with an administration generally favoring deregulation and empowering large corporations. This ideological underpinning is crucial for understanding the policy’s genesis and its implications for future regulatory trends, signaling a broader shift.
Chairman Carr’s public advocacy for repeal, including an op-ed in a conservative news website, further contextualizes the decision within a broader political narrative. He framed the deregulation as a necessary measure for competitive equity, arguing the cap was an “outdated” policy preventing local broadcasters from achieving parity with competitors, especially digital giants. This resonates with a pro-business, anti-regulatory stance.
The explicit mention of conservative-leaning companies such as Sinclair Broadcast Group and Nexstar as primary beneficiaries is not incidental; it highlights the potential for ideological consolidation within the media landscape. While the FCC’s mandate is to regulate in the public interest, the political inclinations of dominant media owners can significantly influence the editorial direction and content offerings across a vast network of stations, thereby shaping public discourse.
This policy change is expected to trigger responses from various institutional stakeholders. Public interest groups and media watchdog organizations are poised to voice strong concerns regarding reduced media diversity, potential degradation of local news quality, and heightened concentration of influence. These groups will likely explore legal challenges or advocate for congressional oversight to mitigate perceived negative consequences and uphold public interest principles.
Congress, having previously adjusted the cap in 2004, retains the ability to re-engage, particularly if consolidation effects are widely perceived as detrimental to the public interest. However, the current political climate and the FCC’s statutory authority grant it significant autonomy in interpreting and applying broadcast regulations, rendering immediate legislative reversal challenging and unlikely in the short term.
The decision also reflects a broader trend in regulatory philosophy, re-evaluating traditional industry-specific regulations in light of technological convergence and the rise of new media platforms. The argument that broadcast television requires greater scale to compete with global streaming services and internet platforms signifies a fundamental shift in how regulators perceive the competitive landscape of modern media.
Implications for the Information Ecosystem
The long-term consequences of this regulatory change extend far beyond corporate balance sheets and market share, profoundly impacting the broader information ecosystem. A more consolidated broadcast landscape risks homogenization of content, particularly in news and public affairs programming, as larger entities prioritize efficiencies through centralized production and shared content over diverse local narratives.
While proponents contend that scale enables greater investment in quality journalism, critics frequently cite evidence that consolidation often results in reduced newsroom staff, fewer investigative reports, and increased reliance on syndicated content rather than original local reporting. This trajectory diminishes the unique and critical role of local television in informing communities and holding local power structures accountable.
The concentration of ownership inherently raises profound questions about viewpoint diversity. Should a few large entities with particular ideological leanings control a significant portion of the nation’s broadcast outlets, it could severely limit the range of perspectives available to the public, potentially influencing political discourse and civic engagement. This concern is particularly amplified given broadcast television’s pervasive reach in local elections and community issues.
For advertisers, while consolidation may streamline **media buying**, it concurrently risks reduced competition among broadcast outlets, potentially driving up advertising costs in local markets. This could disproportionately impact small and medium-sized local businesses reliant on affordable local advertising to reach their customer base, hindering local economic activity.
This shift in regulatory approach establishes a significant precedent for future media policies. Transitioning from clear, quantifiable limits to discretionary, case-by-case reviews could signal a broader trend towards less prescriptive regulation across various sectors, prioritizing market forces and post-hoc evaluations over pre-emptive structural safeguards.
Ultimately, the FCC’s decision to eliminate the 39% ownership cap constitutes a momentous deregulatory action with profound, far-reaching implications for the structure, economics, and public service mission of broadcast television. Its full impact will unfold over time, shaping not only the competitive landscape for media companies but also the quality, diversity, and accessibility of information for the American public.