The Great Decoupling: From AI Tailwinds to Structural Threats
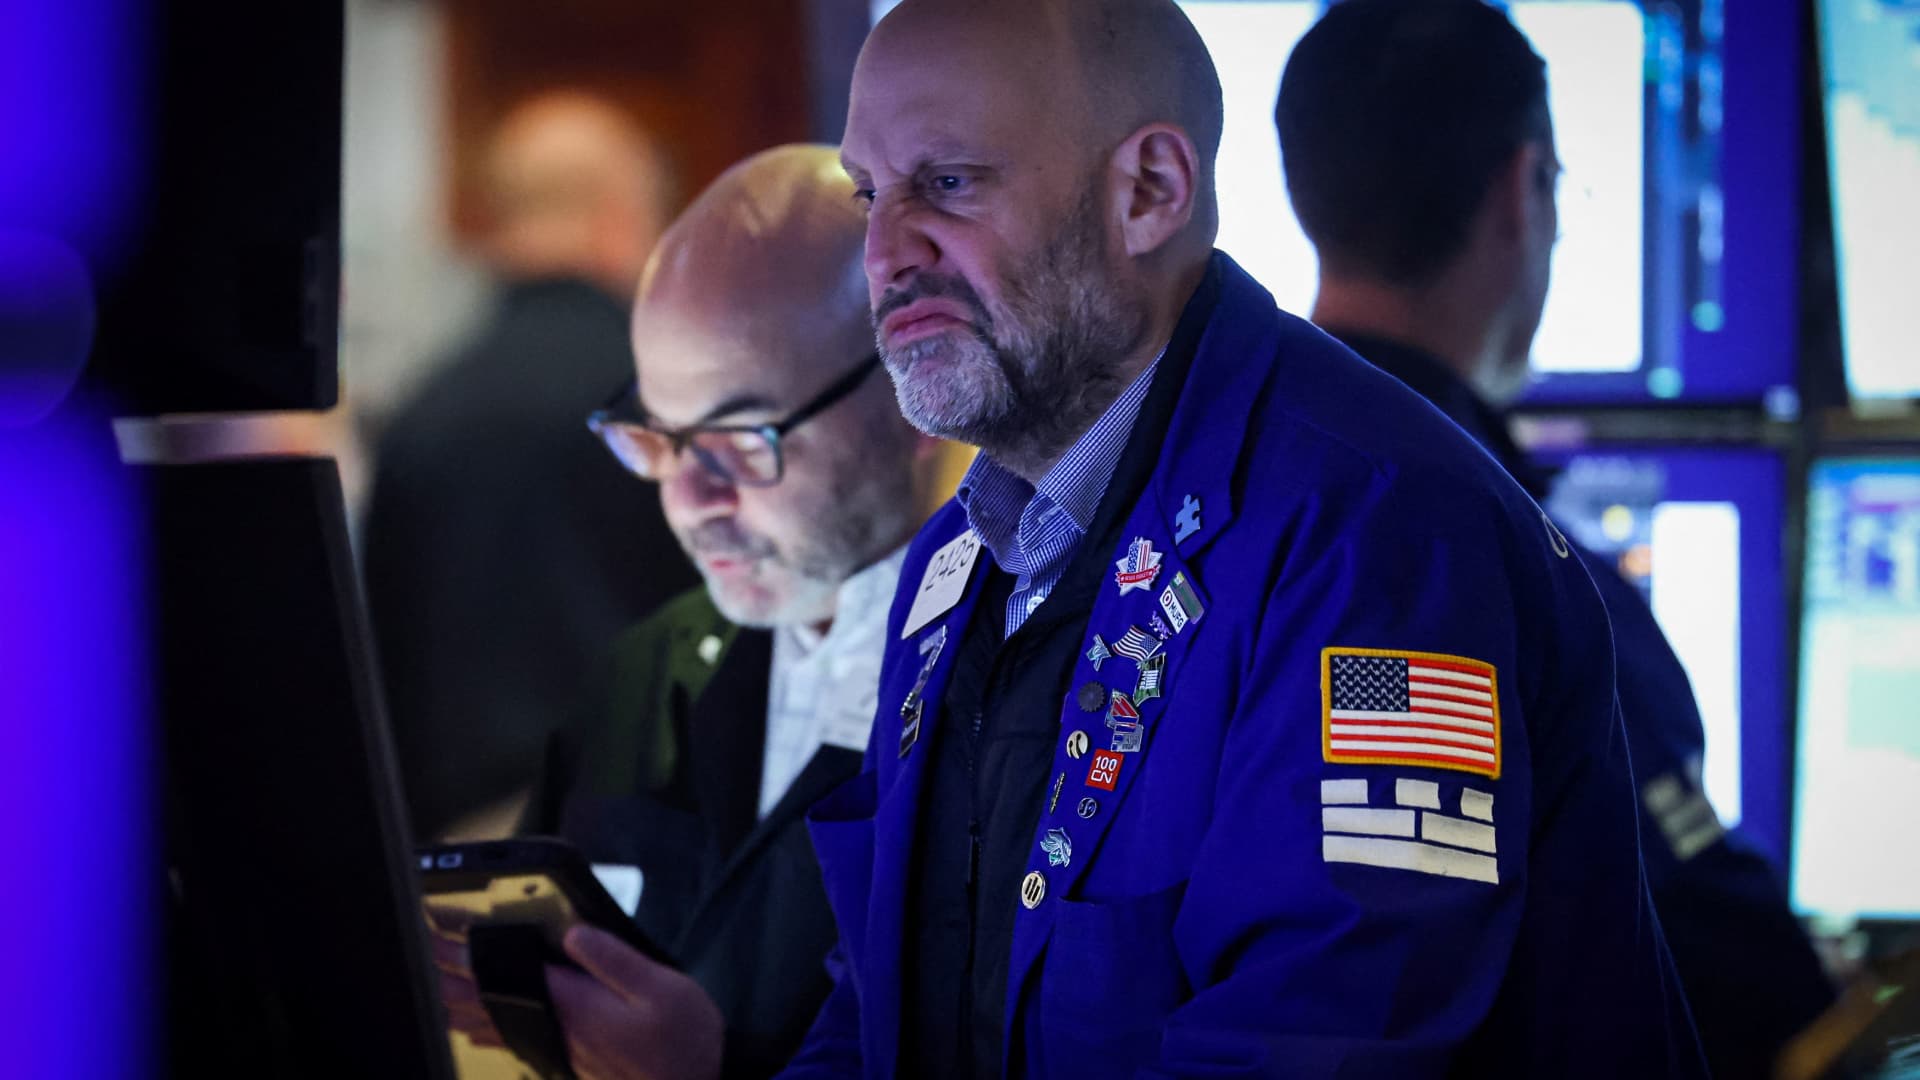
The resumption of trading post-Presidents’ Day has catalyzed a sophisticated re-rating of US equities, characterized by the emergence of ‘AI disruption vigilantes.’ The S&P 500’s 0.8% retracement and the Nasdaq Composite’s 1.1% correction signal a fundamental transition: investors are moving beyond the initial euphoria of AI integration toward a punitive assessment of technological obsolescence. This pivot is most pronounced in the software sector, where the iShares Expanded Tech-Software Sector ETF (IGV) has plummeted 22% year-to-date, reflecting a mass exodus from traditional application-layer providers whose business models appear increasingly fragile.
This volatility stems from a targeted scrutiny of legacy Software-as-a-Service (SaaS) frameworks. Large-scale institutional actors are discounting firms reliant on seat-based licensing or manual workflow management, anticipating that generative AI will either automate these functions or enable enterprises to build bespoke internal solutions. Established players like Salesforce and Autodesk—declining 2% and 3% respectively—face a valuation ceiling as the market questions their long-term pricing power in an ecosystem where LLMs can commoditize specialized software tasks.
Infrastructure as the New Alpha: The Pivot to Power and Utilities
As the ‘application layer’ faces an existential crisis, capital is rotating into the physical infrastructure required to sustain the AI era. The market is increasingly treating energy providers like Constellation Energy as essential AI proxies. This strategic shift acknowledges a critical bottleneck: the scalability of AI is no longer a software limitation but a power grid constraint. Investors are de-risking by moving from speculative software to the ‘utility layer,’ where data center expansion guarantees long-term, high-volume energy contracts.
Even the primary hardware beneficiaries are not immune to this refined discipline. Nvidia, Meta, and Palantir all traded lower as the market enters a discovery phase, attempting to calibrate the speed at which infrastructure investments translate into tangible enterprise-level ROI. The current sentiment suggests that while hardware remains foundational, the market is demanding proof of sustainable margin expansion rather than mere participation in the AI narrative.
Cross-Sector Contagion and the Trillion-Dollar Retail Benchmark
The ‘AI jitters’ have breached the tech perimeter, impacting logistics, real estate, and financial services. In the trucking and logistics sectors, the threat of autonomous optimization is creating a divergence between legacy carriers and tech-integrated incumbents. Simultaneously, Walmart’s entry into the trillion-dollar market capitalization club serves as a litmus test for the retail sector. As Walmart prepares its first quarterly report as a mega-cap entity, the focus shifts to how global scale and AI-driven supply chain efficiencies can defend margins against high interest rates and technological disruption.
This consolidation of power among mega-cap firms indicates a defensive rotation. Institutional investors view trillion-dollar entities as safe havens capable of either out-spending disruptors or acquiring them. The overarching market discipline is clear: valuation is no longer driven by AI potential, but by disruption resilience. Companies failing to articulate a credible defense against AI-driven cannibalization risk sustained valuation compression in an increasingly skeptical financial landscape.