A decisive pivot in U.S.-Iran relations has catalyzed a violent recalibration across global capital markets. The suspension of kinetic operations against Iranian energy infrastructure has effectively dismantled the ‘war premium’ that had previously distorted equity valuations and commodity pricing. This strategic shift from military escalation to ‘productive’ diplomatic engagement suggests a sophisticated effort to decouple global economic stability from regional friction points, providing a much-needed reprieve for inflation-weary central banks.
Institutional Reallocation and the Collapse of Tail Risk
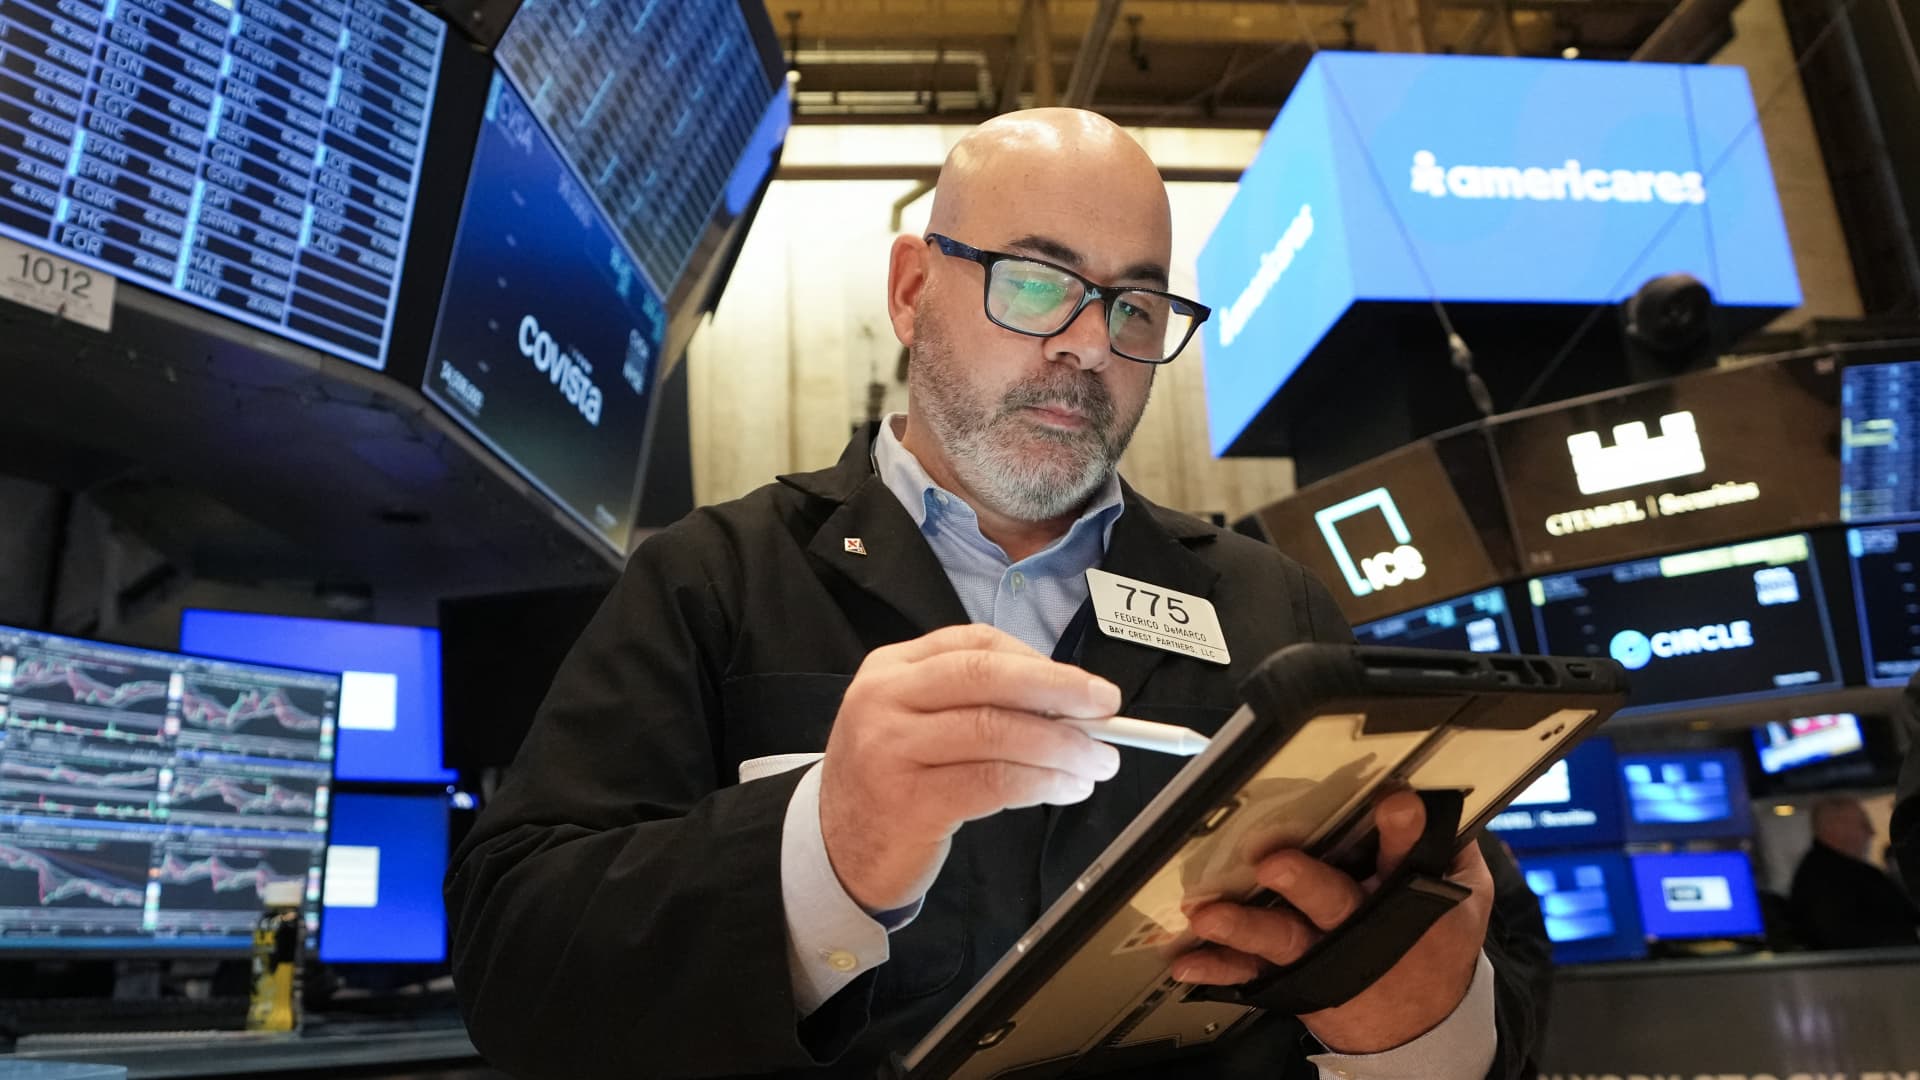
The immediate 950-point surge in Dow Jones Industrial Average futures (2.1%) signifies a rapid exit from defensive positioning. Institutional desks, which had been pricing in extreme tail risks of a total regional conflagration, are now rotating capital back into growth-sensitive sectors. S&P 500 and Nasdaq-100 futures gained 1.9% and 2.1% respectively, as the removal of a major geopolitical bottleneck suggests a stabilization of corporate earnings forecasts that were previously threatened by skyrocketing input costs.
This rally is not merely a relief bounce but a fundamental repricing of risk. By avoiding strikes on Iranian power grids and refineries, the U.S. administration has preserved the operational integrity of the global energy supply chain. Consequently, high-frequency trading algorithms and institutional allocators are discounting the probability of a 2026 global recession, shifting the market narrative from capital preservation to aggressive accumulation.
Commodity Correction: WTI and Brent Crater 9%
The energy sector bore the brunt of this de-escalation, with West Texas Intermediate (WTI) and Brent crude benchmarks both collapsing by 9%. WTI dropped toward $89 per barrel while Brent stabilized near $101. This correction represents the sudden removal of the supply-disruption hedge. As the threat of an Iranian energy blockade recedes, the market is returning to fundamental demand-supply metrics, which currently favor lower prices in the absence of a kinetic catalyst.
For global logistics and manufacturing, this 9% decline serves as a massive de facto stimulus. Lower energy overhead translates directly into reduced transportation costs and cooled producer price indices (PPI). If sustained, this drop could allow the Federal Reserve and the ECB to adopt a more dovish posture, as the primary exogenous driver of recent inflationary pressure has been neutralized through diplomacy rather than monetary tightening.
Strategic Leverage and the Infrastructure Preservation Strategy
The decision to halt strikes on Iranian infrastructure is a masterclass in ‘latent deterrence.’ By keeping Iranian energy assets intact, the U.S. retains significant leverage; the threat of destruction remains a more potent negotiating tool than the destruction itself. This preservation ensures that Iran remains economically viable enough to participate in a ‘complete and total resolution,’ preventing the chaotic spillover effects of a failed state in the Persian Gulf.
Furthermore, the ‘detailed and constructive’ nature of the ongoing talks suggests a transition toward a structured framework. Market participants are interpreting the two-day pause in hostilities as evidence that both Washington and Tehran have identified a mutually beneficial exit ramp. The focus now shifts to verification and the potential for a formal non-aggression pact, which would provide the long-term certainty required for sustained capital investment in the region.
Algorithmic Diplomacy and Information Velocity
The announcement’s dissemination through non-traditional channels highlights the evolving intersection of high-speed diplomacy and market mechanics. Modern trading desks are now forced to integrate social media pronouncements into their risk models with the same weight as official white papers. This creates a high-velocity environment where 950-point moves occur in seconds, punishing laggards and rewarding those positioned for a diplomatic breakthrough.
As the ‘tenor and tone’ of these conversations remain positive, the broader financial ecosystem is moving toward a ‘soft landing’ scenario. The reduction in geopolitical volatility allows for a return to domestic economic fundamentals. While the path to a final resolution remains fraught with historical complexities, the current trajectory has fundamentally altered the 2026 strategic landscape, replacing the specter of war with a credible framework for economic and regional stabilization.
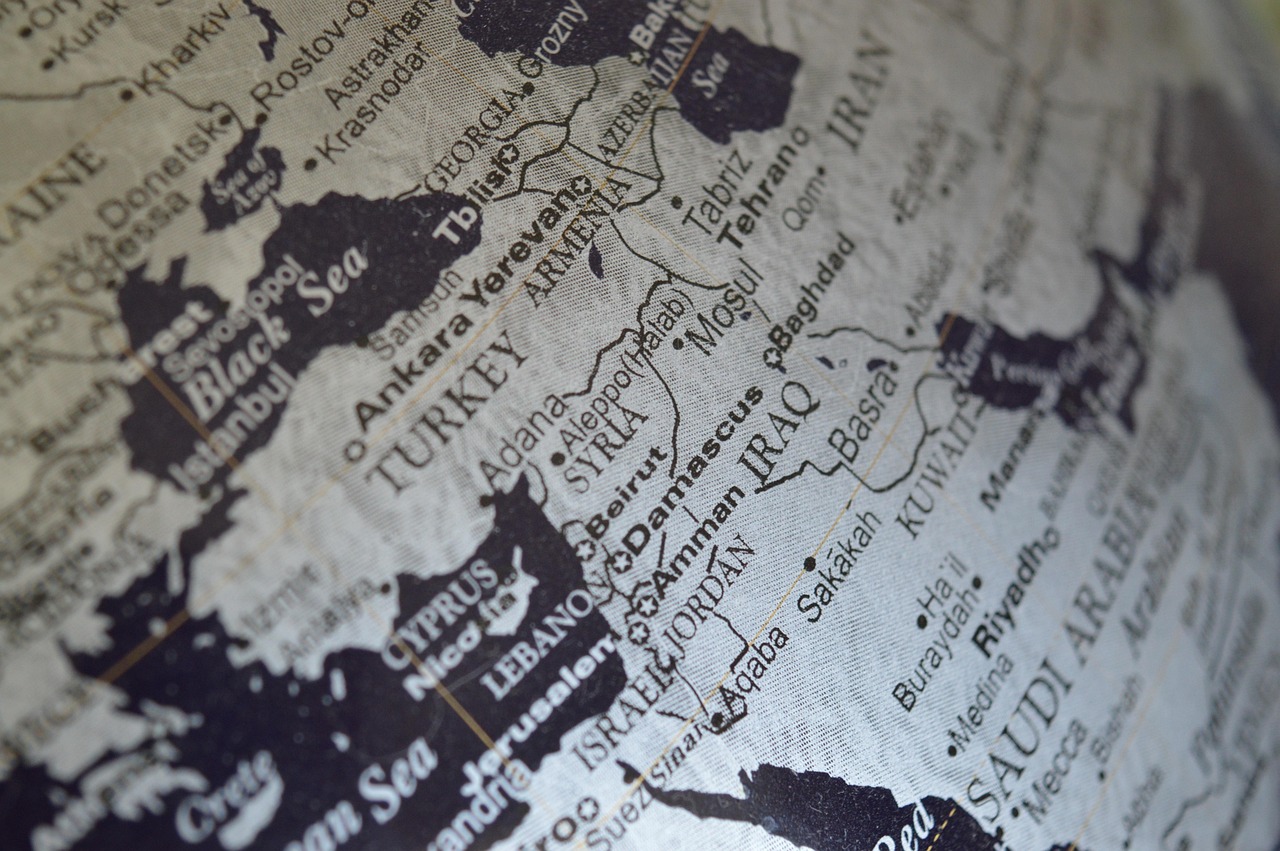
Photo by ErikaWittlieb on Pixabay.