GameStop Q4 Earnings: Declining Retail Revenue vs. Strategic Cash Position
GameStop Corp. (GME) disclosed its Q4 earnings report, revealing a significant 14.8% year-over-year revenue decline to $1.10 billion for the quarter ending January 31. The results indicate ongoing operational challenges for the physical retailer, particularly in core sales segments. However, the stock experienced a slight post-market increase, suggesting that market valuation is less dependent on traditional operational performance metrics and more on the company’s substantial cash position and potential future capital deployment strategies.
This market reaction highlights a fundamental disconnect: traditional valuation models, which focus on revenue growth and operational profitability, conflict with the current market perception of GameStop as a capital allocation vehicle. The focus has shifted from evaluating current sales performance to anticipating how management will deploy its substantial financial resources to navigate structural changes in the gaming industry.
Analysis of Operational Performance and Structural Challenges
A deeper analysis of the earnings report reveals critical operational headwinds. The most significant challenge is the ongoing shift in the company’s sales mix, particularly the decline in hardware and accessories sales. Hardware and accessories accounted for only 48.5% of total sales in the quarter, a notable decrease from 56.6% in the previous year. This segment is crucial for driving customer foot traffic and generating opportunities for higher-margin software and accessory sales.
This reduction in hardware sales as a percentage of total revenue reflects broader structural challenges facing physical retailers in the gaming sector. Consumers increasingly purchase hardware directly from manufacturers or through digital channels, bypassing traditional retail intermediaries. The declining share of hardware suggests that GameStop is struggling to maintain relevance as a primary destination for new console purchases, which directly impacts its ability to drive attachment rates for higher-margin items. The source notes that these challenges underscore a broader set of “continued retail troubles” where the shift to digital distribution fundamentally alters the competitive landscape.
The Strategic Significance of the $9 Billion Cash Position and Capital Allocation Dilemma
The core strategic narrative surrounding GameStop is fundamentally altered by its substantial cash position, reported at $9 billion. This capital reserve provides significant financial stability against operational losses and allows for strategic flexibility not typically available to struggling retailers. The presence of such a large cash hoard transforms the company from a traditional retailer into a potential capital allocation vehicle, creating a high-stakes decision point for leadership regarding capital allocation strategies.
Management faces a classic capital allocation dilemma: initiating a large-scale share buyback program versus pursuing strategic acquisitions (the “M&A wildcard”).
- Share Buybacks: A buyback program would reduce the number of outstanding shares, potentially increasing earnings per share (EPS) and rewarding existing shareholders. Given the high retail investor engagement, this strategy could be perceived as a direct return of capital and may quickly impact share price.
- Strategic Acquisitions (M&A): The alternative involves deploying capital to acquire new businesses or technologies to diversify revenue streams. Potential targets could include companies in digital gaming, e-sports organizations, or technology platforms. This path addresses the underlying structural challenges of the physical retail model but carries significant risks related to identifying accretive acquisitions and successful integration into the corporate structure.
The market’s slight post-market rise suggests an anticipation of a positive catalyst related to this cash deployment, placing pressure on management to deliver a clear and decisive strategy.
Market Sentiment and Future Trajectory
The unique dynamics of the retail investor community surrounding GameStop amplify the impact of non-fundamental factors on its valuation. The high level of retail engagement creates a feedback loop where market sentiment and expectations of a positive catalyst can override traditional financial analysis. The cash position acts as a stabilizer, providing a floor for the stock price and reinforcing the narrative that the company has sufficient resources to weather operational difficulties.
The company’s future trajectory hinges entirely on management’s ability to effectively deploy this capital. The decision between optimizing the existing retail model through buybacks and pivoting to new ventures through strategic acquisitions will define GameStop’s long-term viability. The choice will determine whether GameStop remains a declining physical retailer or successfully transitions into a diversified technology or capital holding company, a transition that carries substantial execution risk for leadership.
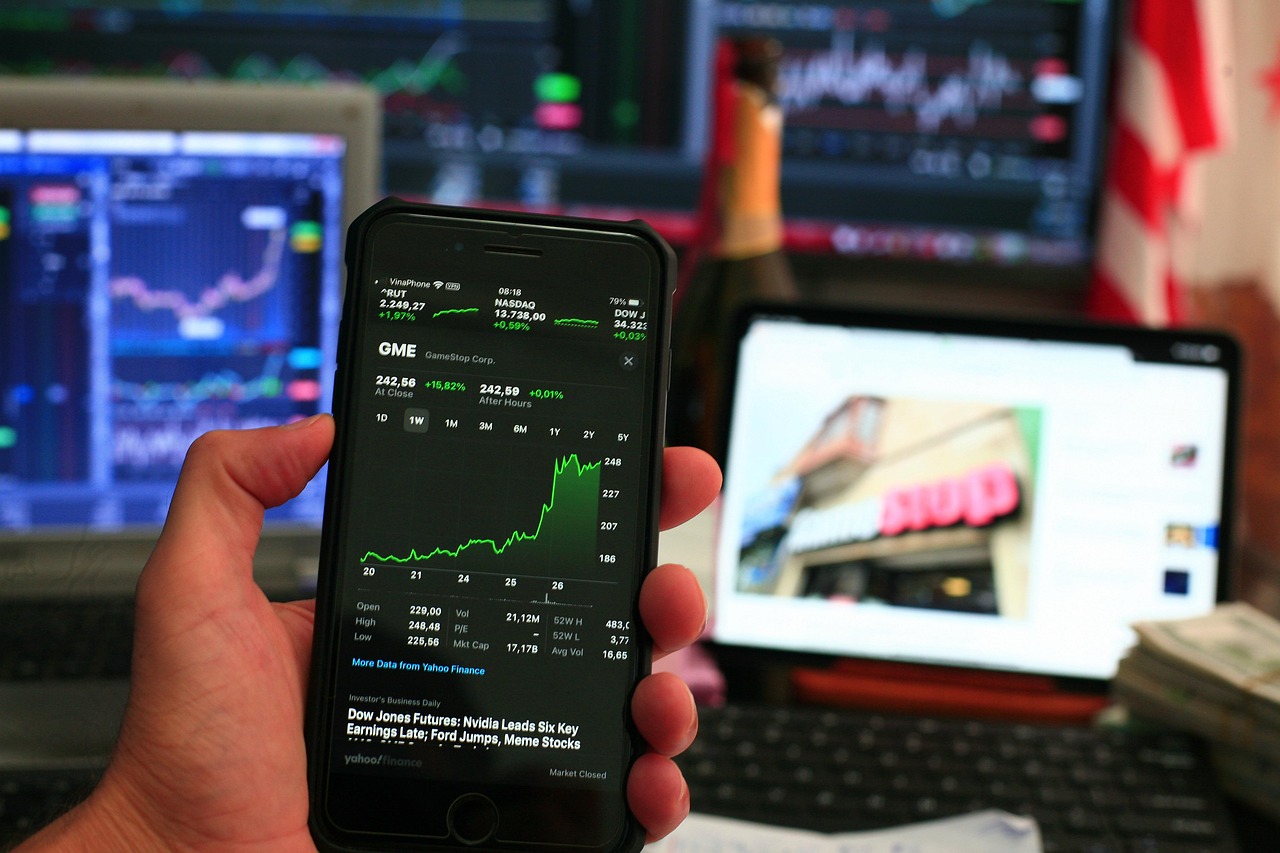
Photo by sergeitokmakov on Pixabay.