The digital world, perpetually in motion, often reveals its most profound shifts with breathtaking speed. Barely a few years ago, the advent of generative artificial intelligence software, epitomized by OpenAI’s ChatGPT in late 2022, felt like a leap into a future imagined only in science fiction. Today, that future is accelerating at an unimaginable pace, transforming industries from healthcare to finance, fundamentally altering how we interact with technology, and even redefining the global economy.
This rapid evolution has not only sparked unprecedented innovation but has also ignited a fierce scramble for the foundational hardware that makes AI possible. At the core of this infrastructure lies memory, the unsung hero enabling the processing of colossal datasets. This pivotal role has created extraordinary opportunities and, inevitably, new complexities and risks in the fiercely competitive stock market, particularly for companies that supply these crucial components.
Micron’s Meteoric Ascent: The AI Catalyst
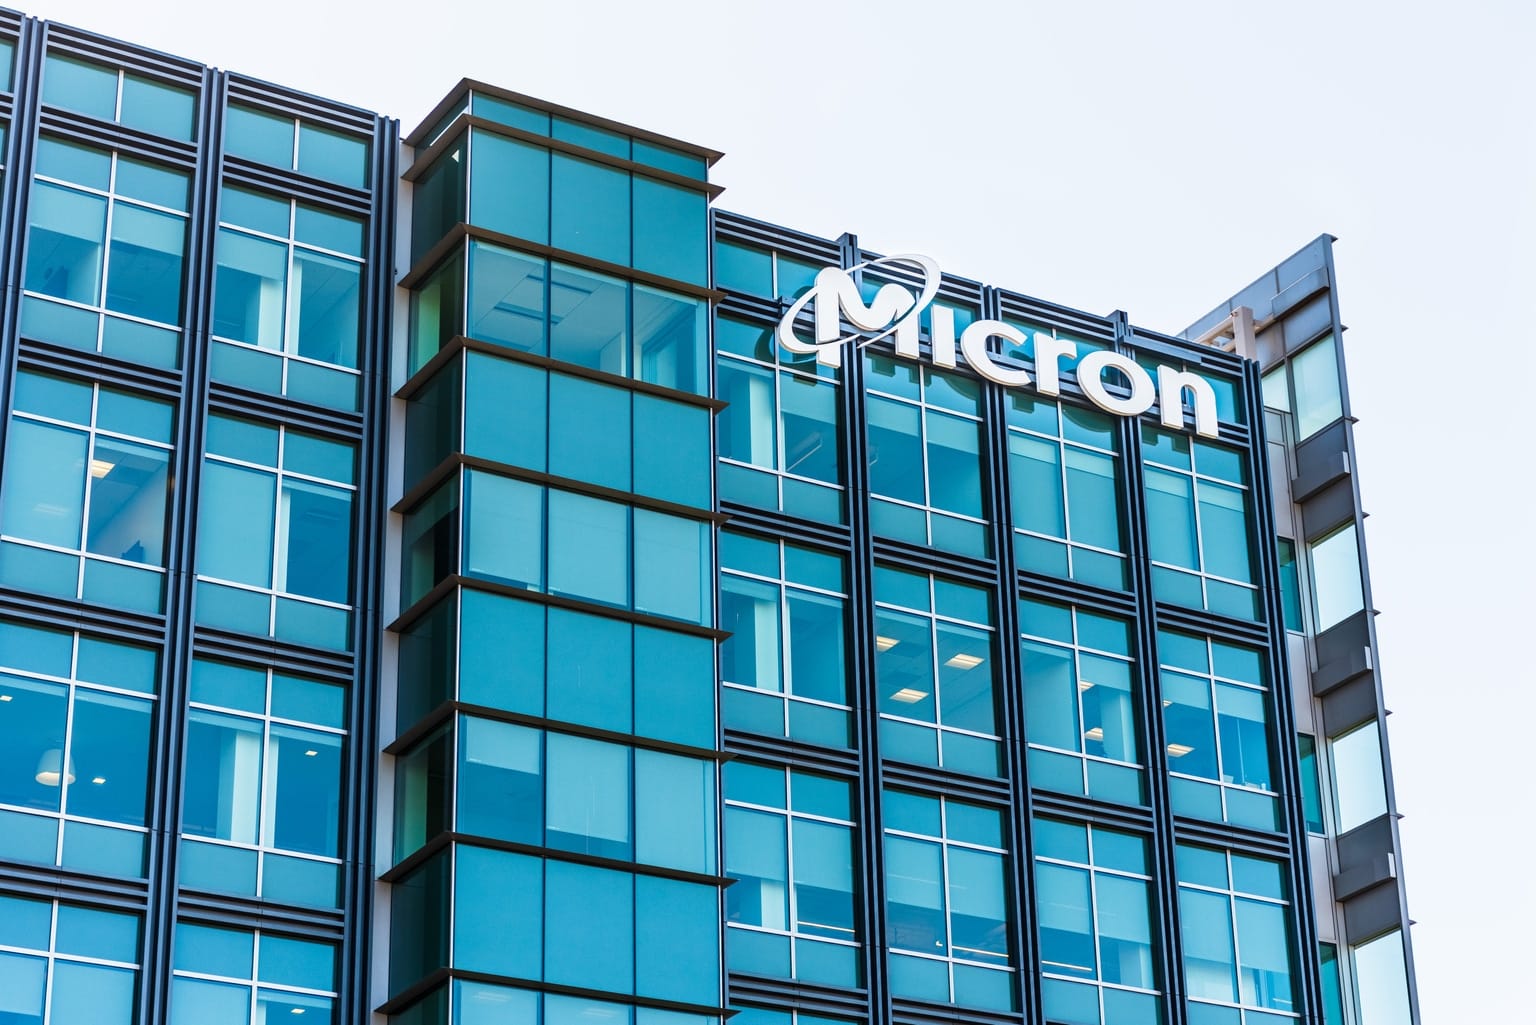
Amidst this transformative era, one company has steadily emerged from the shadow of more publicly lauded tech giants to capture the market’s fervent attention: Micron Technology, Inc. (MU). Its shares, providing the essential memory infrastructure demanded by AI, embarked on an extraordinary trajectory, tripling in value throughout 2025. This spectacular surge dramatically outpaced even the revered Wall Street favorite, NVIDIA Corporation (NVDA), a company widely synonymous with AI processing power.
Micron’s remarkable performance has propelled it into the financial spotlight, sparking a fervent and often polarized debate among investors worldwide. Is this merely the beginning of a sustained ascent, positioning Micron as an undeniable market leader by the end of 2026, a testament to its indispensable role in the AI revolution? Or does the blistering pace of its climb signal an impending peak, making it “time to sell” before a potential “bust cycle” that has historically plagued the semiconductor industry?
The Insatiable Hunger of Generative AI
The engine driving this technological revolution is data, and generative AI’s insatiable appetite for it is fundamentally rewriting the rules for hardware manufacturers. Technologies like ChatGPT, capable of understanding and generating human-like text, are just one facet of a broader AI landscape that includes complex image and video generation, advanced scientific discovery, drug development, and autonomous systems. Each of these applications requires colossal amounts of computational power and, crucially, high-bandwidth memory to function effectively and efficiently.
Every query submitted to an AI model, every analysis performed on a massive dataset, and every creative output generated demands rapid access to vast repositories of information. This also necessitates the ability to process these data streams simultaneously and at lightning speeds, pushing the absolute limits of existing infrastructure. Latency, or the delay in data transfer, can severely cripple AI performance, making advanced memory solutions paramount.
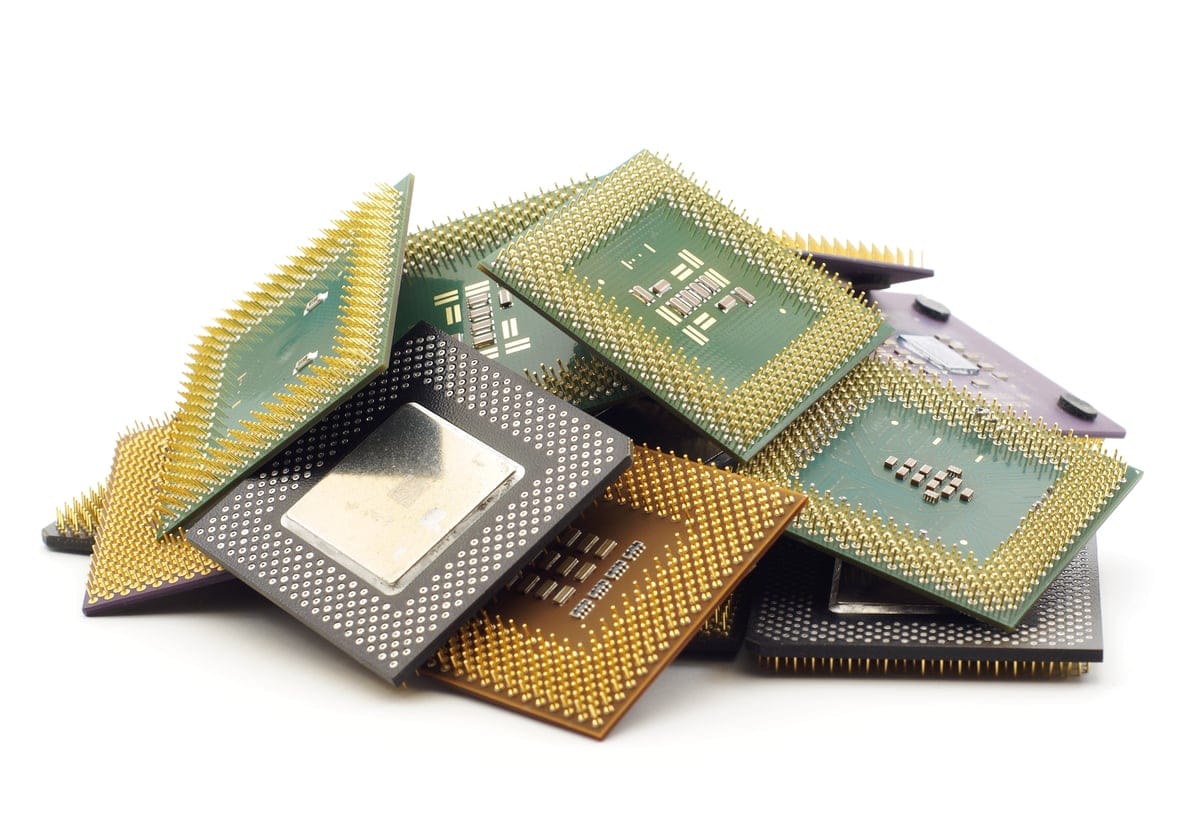
Micron, a recognized global leader in advanced memory and storage solutions, finds itself strategically positioned at the very epicenter of this unprecedented demand surge. Its portfolio, encompassing cutting-edge DRAM (Dynamic Random-Access Memory) and NAND flash storage, offers more than just components; they are the fundamental bedrock upon which sophisticated AI algorithms operate. High-performance memory from Micron is vital for AI data centers, which serve as the nerve centers of the AI revolution. These centers rely heavily on Micron’s technology to train increasingly complex models and deploy them across vast networks efficiently, thereby solidifying the company’s role as an indispensable, though often behind-the-scenes, enabler in the global AI race.
From Undervalued to Market Sensation: Micron’s Journey
The journey of Micron’s stock over the past couple of years has been a compelling testament to the market’s awakening to its pivotal and expanding role in the tech ecosystem. Just a short while ago, in August 2024, a notable bullish sentiment emerged, with analyses suggesting the company’s shares, then trading around $89, were significantly undervalued. At that specific juncture, while the immense potential of artificial intelligence was generally acknowledged, the full extent of its hardware implications, particularly the burgeoning demand for high-performance memory, was still crystallizing for many investors.
The market, in essence, was perhaps yet to fully grasp the exponential growth in demand for memory chips that the AI boom would undeniably unleash. This period likely represented a trough following earlier cyclical downturns common in the semiconductor industry, offering an attractive entry point for farsighted investors who could foresee the coming wave of AI-driven demand. Micron’s foundational technology, already critical for traditional computing and data storage, was poised for a new era of indispensability.
What followed this period of perceived undervaluation was a powerful and sustained rally, culminating in Micron’s shares achieving the extraordinary feat of tripling throughout the calendar year 2025. This exceptional performance not only handsomely rewarded early believers who saw value at $89 but also firmly established Micron as a formidable force in the broader tech market. Its growth trajectory during this period was so significant that it even surpassed that of NVIDIA, a company whose graphics processing units (GPUs) are the very engines of AI computation, highlighting the critical and often overlooked role of memory in the AI stack.
Such an impressive leap in valuation and market recognition has naturally led some analysts and investors to boldly predict that Micron could indeed become a genuine market leader by the end of 2026. This optimism is often fueled by its seemingly attractive valuation metrics, such as a reported 11.7 P/E (price-to-earnings) ratio, which for a company experiencing such explosive growth, might appear modest. A lower P/E ratio, in simple terms, suggests that investors are paying less for each dollar of the company’s earnings, which can be an incredibly attractive proposition for those seeking growth at a reasonable price, positioning it as “one of 2026’s best buying opportunities” for those still assessing the landscape.
The Investor’s Conundrum: Riding the Wave or Preparing for the Pullback?
Yet, in the notoriously volatile world of high-growth technology and semiconductors, every new summit raises fundamental questions about the sustainability of the path ahead. The very intensity of Micron’s rally, pushing its share price significantly higher—implicitly towards the $400 mark that some analyses now warn against—has triggered a compelling counter-narrative. Some seasoned investors, well-versed in market history and witnessing the dizzying ascent, are now openly pondering whether it’s “time to sell before a potential bust cycle” takes hold.
This cautious perspective is deeply rooted in the semiconductor industry’s historically cyclical nature, a pattern characterized by periods of booming demand and rapid expansion often followed by phases of oversupply, intensified competition, and subsequent price corrections. The memory sector, in particular, has experienced dramatic swings, with significant capital expenditures leading to manufacturing capacity increases, which can then exceed demand, depressing prices and profitability for all players.
The concern among those advocating caution isn’t necessarily about Micron’s technological prowess or the enduring, long-term demand for AI itself. Rather, it’s keenly focused on the pace of recent growth and the potential for market exuberance to temporarily outstrip fundamental realities. A “bust cycle” typically involves a confluence of factors: a temporary slowdown in overall enterprise IT spending, an accumulation of inventory across the supply chain, and the inevitable downward pressure on average selling prices for memory chips, all of which can severely impact a company’s revenue and profit margins. For a company whose stock has tripled in a single year, the risk of a significant correction becomes a very real consideration, especially for those looking to lock in substantial, short-term gains and mitigate future downside.
Balancing Opportunity with Inherent Risk
Navigating this complex investment landscape requires a keen understanding of both revolutionary technological trends and the often-irrational nuances of market psychology. On one hand, the underlying demand for high-performance memory, driven by the ever-expanding universe of AI applications, represents a powerful, long-term structural shift, far from a fleeting fad. As AI permeates more aspects of daily life, from personalized medicine to smart cities, and as “edge AI” processing becomes commonplace in devices from smartphones to industrial sensors, the need for faster, more efficient, and denser memory will only intensify, providing a formidable and sustained tailwind for companies like Micron.
The argument for Micron as a “best buying opportunity” at a seemingly modest 11.7 P/E ratio, especially when compared to the often significantly higher valuations of other pure-play AI software or GPU companies, suggests that, even after its significant run, the company’s earnings potential might still be undervalued relative to its peers or future growth prospects. A lower P/E implies that investors are currently paying less for each dollar of the company’s earnings, which, for a rapidly growing entity, can indicate that the market has not yet fully priced in its future profit expansion.
On the other hand, the annals of market history are replete with examples of high-flying tech stocks, even those with undeniable long-term potential, succumbing to sharp market corrections. The fear of a “bust cycle” is a legitimate and historically informed concern for a sector that has repeatedly exhibited boom-and-bust patterns. For investors who astutely bought into Micron at $89 and now see their holdings approaching implied targets around $400, the temptation to de-risk, realize substantial profits, and potentially reinvest during a future downturn is undeniably strong. The core of this dilemma lies in accurately discerning whether the current valuation fully discounts future growth and innovation, or if it incorporates an element of speculative froth that could quickly dissipate in the face of macro-economic headwinds or increased competition.
The market’s narrative around Micron, therefore, is a complex and captivating tapestry, intricately woven with threads of revolutionary technology, unprecedented demand, spectacular financial performance, and the ever-present specter of market cyclicality. It perfectly embodies the exhilarating promise and inherent unpredictability that define investment in cutting-edge innovation, where conviction must always be tempered with caution.
“The journey of high-growth technology stocks like Micron is a perpetual balancing act,” observed one seasoned market analyst, reflecting on the broader tech landscape. “It requires navigating between riding the undeniable wave of disruptive innovation and respecting the immutable, often unforgiving, laws of market cycles. The truly astute investor understands that opportunity and risk are not just two sides, but often inextricably linked facets, of the same rapidly evolving coin.”